





《CLARITY法案》が成立:イーサリアムが最大の勝者に?
原文作者:Adriano Feria
原文编译:佳欢,ChainCatcher
Senate Banking Committee released the full 309-page revised text of the Digital Asset Market Clarity Act on May 12.
Most coverage will focus on which tokens failed the new decentralization test, which issuers will face new disclosure burdens, and which projects need to restructure within the four-year transition certification window. Such reporting is not wrong, but it is incomplete.
The more important story lies in the Act's impact on the one asset that passed every single criterion of the test and happens to be the only one with a functional programmable smart contract platform.
Once this framework becomes law, Ethereum will occupy a regulatory category within the U.S. legal system where it is the sole member. The two dominant bearish narratives for ETH that have shaped the market over the past five years will simultaneously collapse, and the market has yet to price this in.
Two Bills, One Framework
Before delving into the substance, it is necessary to briefly review the broader regulatory architecture, as public discussion often conflates two distinct pieces of legislation.
The GENIUS Act (Guiding and Establishing National Innovation for U.S. Stablecoins Act) was signed into law by the President on July 18, 2025.
It establishes the first federal regulatory framework for payment stablecoins: requiring 1:1 reserves with liquid assets, monthly reserve disclosures, federal or state licensing for issuers, a ban on algorithmic stablecoins, and a key restriction that stablecoin issuers cannot directly pay interest or yield to holders.
The GENIUS Act covers USDC, USDT, and bank-issued stablecoins. It covers nothing else.
The CLARITY Act covers everything remaining. It addresses SEC and CFTC jurisdictional divisions, decentralization tests for non-stablecoin tokens, exchange registration, DeFi rules, custody rules, and the ancillary asset framework.
These two acts are complementary parts of a broader regulatory architecture.
Most financial media coverage of the CLARITY Act focuses on stablecoin yield, as Title IV's section on "Preservation of Stablecoin Holder Rewards" was the political flashpoint that nearly killed the bill.
Banks pushed to prohibit indirect yield through exchanges and DeFi protocols, because yield-bearing stablecoins compete with bank deposits. Crypto exchanges strongly advocated for preserving this feature. The bipartisan compromise reached on May 1, 2026 cleared the bill's path, but it remains in a delicate state after several delays in consideration.
This debate is important, but it is only one part of a nine-title bill. For anyone actually holding and trading non-stablecoin tokens, the more far-reaching provisions are hidden in Section 104, and almost no one is discussing its second-order effects on asset valuation.
The Five Tests
Section 104(b)(2) of the Act instructs the SEC to weigh five criteria when determining whether a network and its token are under coordinated control:
Open digital system. Is the protocol publicly available open-source code?
Permissionless and credibly neutral. Can any coordinating group censor users or grant themselves hardcoded priority access?
Distributed digital network. Does any coordinating group beneficially own 49% or more of the circulating tokens or voting power?
Autonomous distributed ledger system. Has the network reached a state of autonomy, or does someone retain unilateral upgrade power?
Economic independence. Is the primary value capture mechanism actually functioning?
A network that fails this test will produce a "network token" that is presumed to be an "ancillary asset," meaning the token's value depends on the entrepreneurial or managerial efforts of a specific promoter.
This classification triggers semi-annual disclosure obligations, insider resale restrictions modeled on Rule 144, and initial offering registration requirements. Secondary market trading on exchanges can continue uninterrupted.
The 49% threshold is the core data point, and it is far more lenient than the House version of the CLARITY Act's 20% red line. Networks that fail the test under the 49% threshold do so for genuine structural reasons, not technicalities.
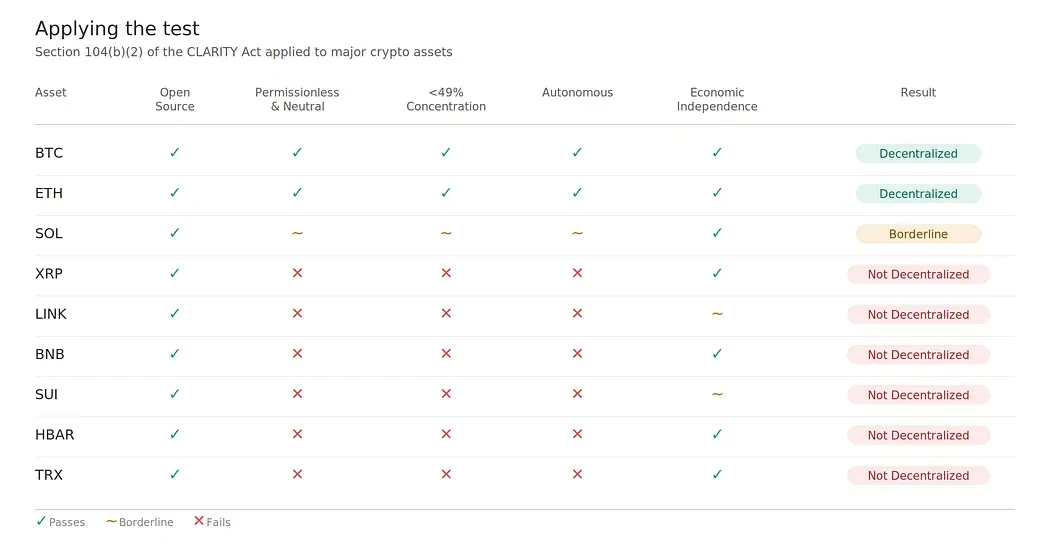
Bitcoin and Ethereum pass all criteria without controversy. Solana hovers on the edge, with the Foundation's influence over upgrades, the heavy allocation to early insiders, and a history of coordinated network pauses running counter to the standards of autonomy and credible neutrality.
Every other major smart contract platform fails for structural reasons that are not easily corrected. This list includes XRP, BNB Chain, Sui, Hedera, and Tron, and extends to most L1 competitors.
Among the assets that pass the test, exactly one has a functioning native smart contract economy.
The Shift in Valuation Regime
Tokens trade on two fundamentally different valuation frameworks.
The first is the commodity/currency premium regime, where value derives from scarcity, network effects, store of value properties, and reflexive demand, with no fundamental-based valuation ceiling.
The second is the cash flow/equity regime, where value derives from revenue capitalized through standard multiples and is subject to strict ceilings imposed by real revenue forecasts.
Most non-Bitcoin tokens have been in a strategic gray area between these two regimes, marketing themselves under whichever framework produces a higher valuation. The CLARITY Act ends this ambiguity through three mechanisms.
First, disclosure requirements impose a cognitive framework. Section 4B(d) requires semi-annual disclosures including audited financial statements (above $25 million), a CFO's going concern statement, a summary of related party transactions, and forward-looking development costs.
Once a token has SEC filings akin to a 10-Q, institutional analysts will evaluate it as they would any entity filing a 10-Q. The format of the filing determines the valuation framework.
Second, the legal definition itself is a qualitative act. An ancillary asset is defined as a token "whose value depends on the entrepreneurial or managerial efforts of the ancillary asset promoter." This definition is conceptually incompatible with a currency premium, which requires value to be independent of any issuer's efforts.
A token cannot be legally classified as an ancillary asset while credibly claiming a currency premium pricing power.
Third, visible scarcity is fragile scarcity. Currency premiums are reflexive, and reflexivity requires a credible scarcity narrative that the market can collectively believe.
When a token discloses its treasury, named insider unlock schedules, and quarterly reports on related party transactions to the SEC, its scarcity story becomes visible; once visible, reflexivity disappears. Investors can see exactly how much insiders hold and when those tokens will be sold. This visibility kills buying pressure.
The result is a two-tier market. Tier 1 assets trade on a currency premium with no fundamental-based valuation ceiling. Tier 2 assets trade on revenue multiples with reasonable valuation caps.
Tokens currently priced on Tier 1 logic but relegated to Tier 2 will face a structural re-rating. For tokens with weak fundamentals but valuations primarily driven by narrative, typified by LINK and SUI, this re-rating could be very severe.
The End of the Two Major ETH Bearish Theses
For five years, the bearish case for ETH rested on two pillars.
The first thesis held that ETH would ultimately be classified not as a commodity but as a security. The pre-mine, the Foundation's continued influence, Vitalik's public role, and the post-merge validator economics gave the SEC ample grounds to act if it chose.
Every bullish case for ETH had to discount the tail risk that institutional capital channels might be restricted.
The second thesis held that ETH would be displaced by faster, cheaper smart contract platforms. Each cycle produces new "Ethereum killers" like Solana, Sui, Aptos, Avalanche, Sei, and BNB Chain, each selling on better user experience and lower fees.
This argument posited that ETH's technical limitations would force economic activity to migrate, diluting its value capture capability.
The CLARITY Act not only weakens these bearish theses but structurally overturns them.
The first thesis collapses because ETH cleanly passes all five criteria in Section 104. No coordinated control, ownership concentration far below 49%, no unilateral upgrade power post-merge, fully open source, and a functioning value capture mechanism.
The regulatory tail risk that has long justified a discount on ETH evaporates.
The second thesis collapses in a more interesting way. "Ethereum killers" can only compete with ETH if they adopt the same valuation framework.
If SOL is certified as decentralized, competition continues. If it fails the test (as all other major smart contract competitors currently appear destined to do), they will be forced into the Tier 2 valuation framework while ETH remains in Tier 1.
The competitive landscape is therefore transformed. Tier 2 assets cannot compete with Tier 1 assets on currency premium, because the core meaning of Tier 1 is that it is not subject to fundamental-based valuation ceilings.
Faster, cheaper L1 chains can still win in specific verticals for transaction throughput and developer attention. But they cannot win on the asset valuation framework that determines L1 market cap.
The Only Ticket
Among assets that pass Section 104's tests, Ethereum is the only one with a functioning native smart contract economy. Bitcoin passes, but its base layer does not support programmable finance.
Every smart contract platform with meaningful TVL fails one or more tests substantively. This includes Solana, BNB Chain, Sui, Tron, Avalanche, Near, Aptos, and Cardano.
Thus, the Act creates a new regulatory category: decentralized digital commodities with native smart contract economies, currently with only one member.
Every traditional financial institution exploring tokenization, settlement, custody, or on-chain finance needs two things: programmability and regulatory clarity.
Before CLARITY, these attributes were strictly separated. Bitcoin had clarity but was not programmable. Smart contract platforms were programmable but legally ambiguous. After CLARITY, Ethereum becomes the only asset offering both properties within a single legal classification.
Once the framework is in effect, anyone building tokenized treasuries, tokenized funds, on-chain settlement infrastructure, or institutional-grade DeFi onboarding will have a clear preferred base layer.
This preference is not aesthetic or technical. It is compliance-driven. Asset managers, custodians, and bank-affiliated funds operate within legal frameworks that favor commodity-class assets and disfavor security-like assets.
Institutional capital flows follow asset classification, and the classification has narrowed to a single programmable asset.
The Sound Money Question
Once BTC and ETH share Tier 1 classification, it is necessary to closely examine their comparative monetary properties, because conventional wisdom has the causal relationship backwards.
The preference for Bitcoin has always rested on its nominally fixed supply schedule of 21 million and its predictable halving every four years. As a scarcity narrative, this is indeed very valuable, and the simplicity of this story is one reason BTC was the first to attain a currency premium.
But BTC's supply model also carries three structural burdens rarely mentioned in discussions of scarcity.
First, mining creates continuous structural selling pressure. Network security depends on miners covering real-world operating costs: electricity, hardware, hosting, and financing.
These costs are denominated in fiat currency, meaning miners must continuously sell a significant portion of newly issued BTC into the market regardless of price.
This selling is permanent, price-insensitive, and embedded in the consensus mechanism itself. It is the cost of maintaining the Proof-of-Work security model.
Second, BTC offers no native yield. Holders seeking yield must either lend BTC to counterparties (introducing credit risk) or move it to non-BTC platforms (introducing custody and cross-chain bridge risk).
The opportunity cost of holding yieldless BTC compounds over time relative to assets that generate native yield. For institutional holders whose performance is measured against yield-inclusive benchmarks, this is a real and persistent drag.
Third, the declining cliff of mining subsidies is a long-tail risk to the decentralization that qualifies BTC for Tier 1 classification.
Block rewards halve every four years and approach zero by 2140, but actual pressure arrives much sooner. By the 2030s, subsidy revenues will be a fraction of today's levels, and the network must rely on fee revenue to make up the difference for security.
If fee markets fail to develop adequately, the lowest-cost miners will consolidate, miner concentration will rise, and the credible neutrality decentralization valued by Section 104 will begin to erode. This is not an imminent risk, but a structural risk that BTC's model has not addressed.
Ethereum reverses each of these properties.
ETH has variable issuance with no fixed cap, the core argument sound money purists use against it. This argument is superficial.
What truly matters to holders is the rate of change in their share of the total supply, not whether the supply schedule has a fixed terminal value.
Under Ethereum's post-merge design, all issued tokens are distributed as staking rewards to validators. Validators have historically earned yields higher than the inflation rate, meaning anyone who stakes can maintain or increase their share of the total supply over time.
For anyone participating in a validator node or holding liquid staking tokens, the "infinite supply" argument is rhetorically forceful but mathematically unsound.
The structural selling pressure that burdens BTC does not exist on the same scale for ETH. Validator operating costs are negligible relative to their rewards. Solo staking requires a one-time hardware purchase and minimal ongoing electricity. Liquid staking and pooled staking abstract away even these costs.
Newly issued tokens accrue to validators and are largely retained rather than sold into the market to cover costs. The same security model that distributes rewards to holders also avoids the price-insensitive selling required by Proof of Work.
The subsidy cliff problem is also absent. Ethereum's security budget scales with the value of staked ETH and is funded through ongoing issuance and fee revenue. There is no predetermined date when security funding abruptly dries up.
This model is self-sustaining, whereas BTC's model increasingly depends on the development of fee markets, the realization of which remains uncertain.
None of this is to argue that ETH will replace BTC. They serve different roles in institutional portfolios.
BTC is a simpler, clearer, politically more defensible scarcity asset. ETH is productive monetary collateral that rewards holders for participating in its security.
The key point is that the conventional view, that BTC has "harder money" properties than ETH because of its fixed supply cap, collapses under scrutiny.
ETH's variable issuance combined with native yield provides holders with better actual economic properties than BTC's fixed supply combined with zero yield, and it does so without structural selling pressure or long-term security funding risk.
For institutional allocators building exposure to Tier 1 crypto assets, this matters significantly. The case for ETH alongside BTC is










