





Hash Global 창립자: 왜 나도 모든 ETH를 청산하기로 선택했는가?
Original Author: HashGlobal KK, Founder of Hash Global
Original Translation: Jiahuan, ChainCatcher
The author has cleared all ETH positions. This article was published on May 24.
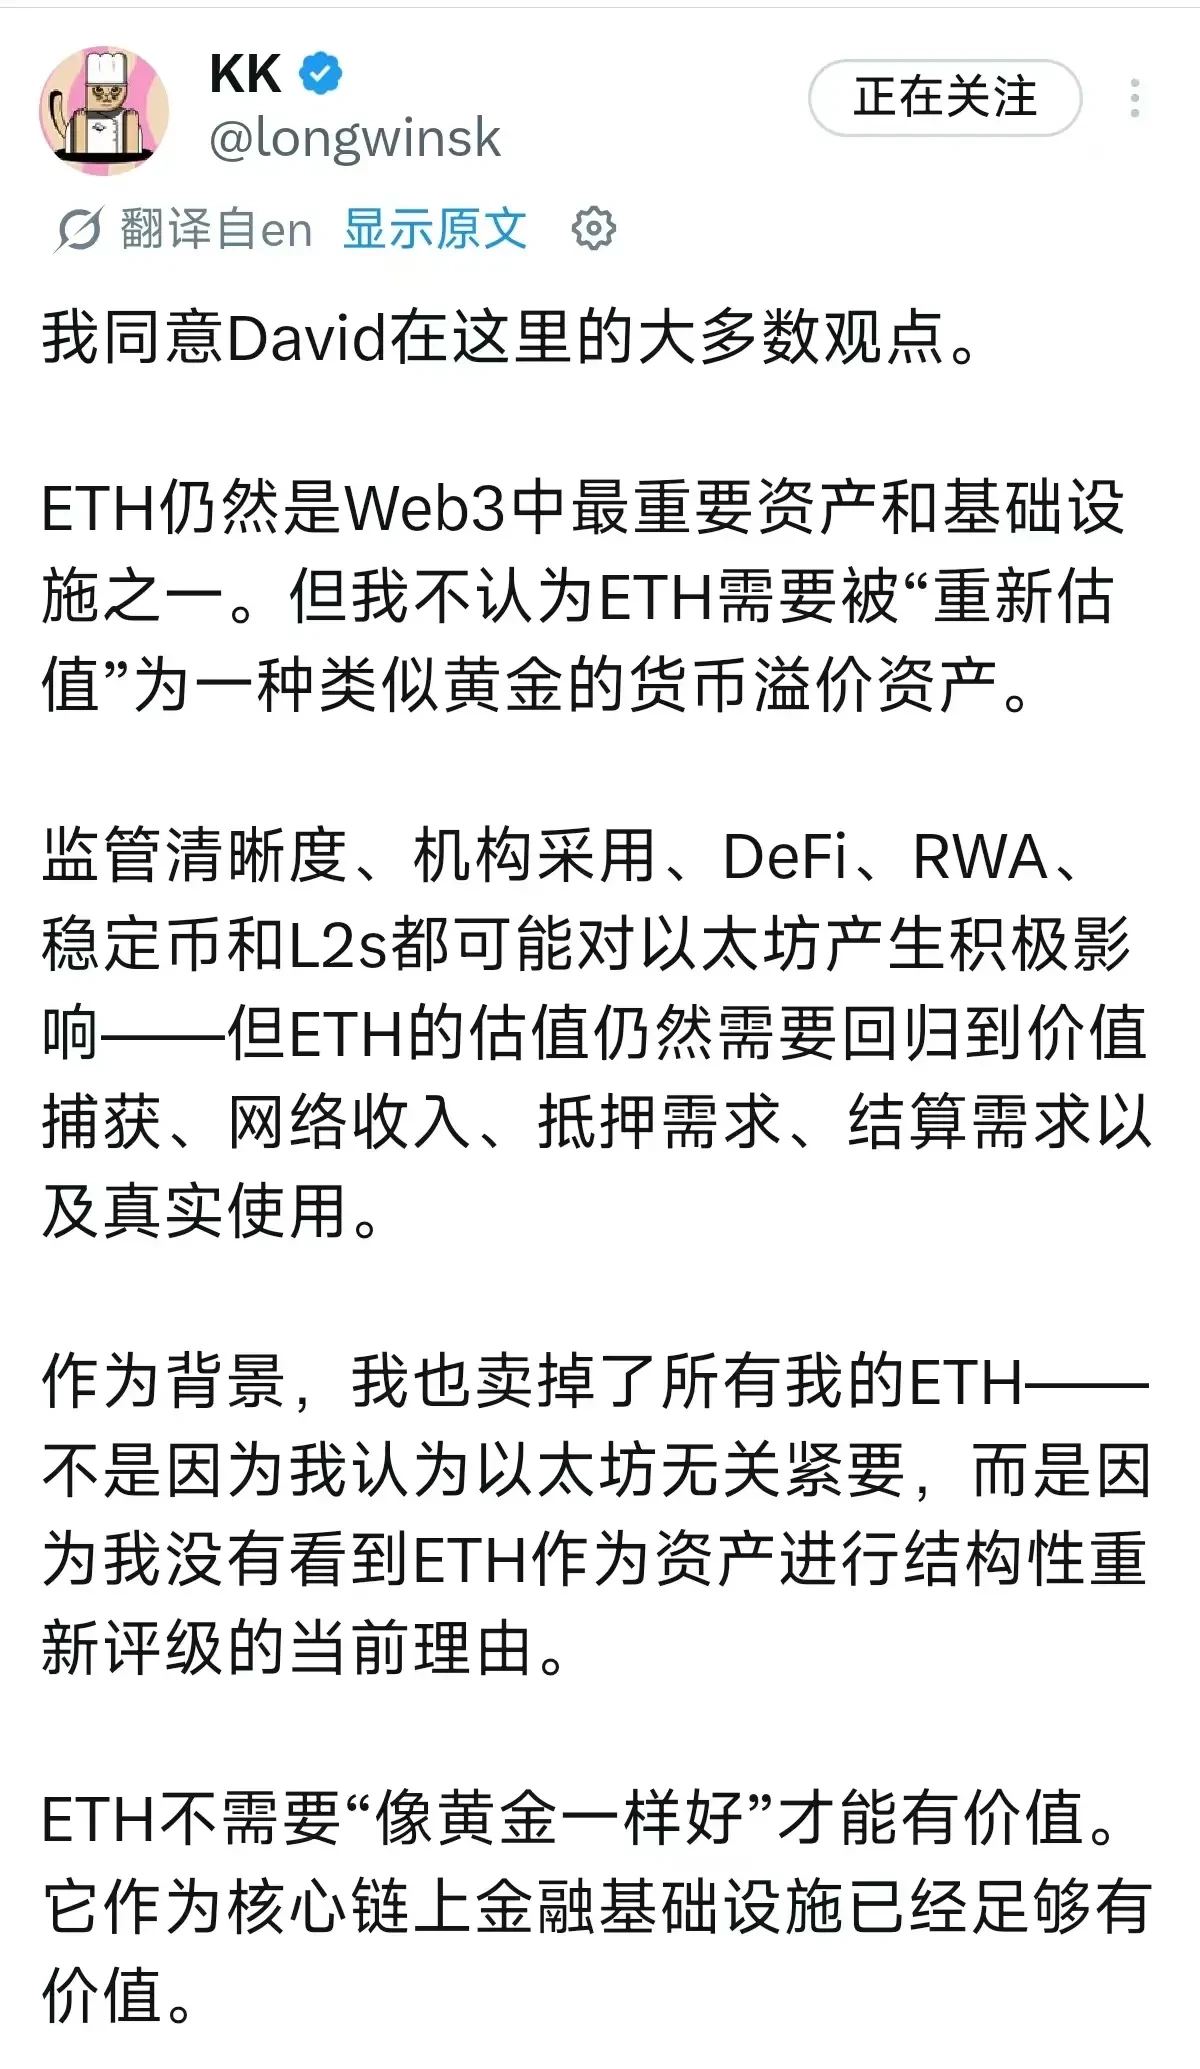
Recently, I read an article arguing that if the US CLARITY Act passes, Ethereum will be the biggest winner.
Its core argument is that ETH could become the only asset under the US regulatory framework that possesses both the attributes of a "decentralized digital commodity" and a "programmable smart contract platform." Therefore, ETH's valuation framework should shift from network revenue logic to a monetary premium logic similar to BTC, gold, or even sovereign reserve assets.
I find this perspective insightful, but the conclusion may be a bit over-extended.
This is not to say I am bearish on ETH or denying the positive impact of CLARITY.
On the contrary, regulatory clarity is undoubtedly a significant positive for ETH. It will reduce compliance concerns for institutional allocation of ETH and help further develop ETFs, custody services, staking, institutional DeFi, RWA, and on-chain settlement businesses.
However, regulatory clarity does not equal a monetary premium.
CLARITY might solve ETH's "regulatory discount" problem, but it won't automatically unlock valuation space associated with gold, real estate, or global reserve assets.
These are two entirely different things and should be analyzed separately.
1. The Market Hasn't Bought This Logic Yet
If ETH were truly perceived by the market as "programmable gold" or an "interest-bearing monetary asset," its valuation should be much closer to BTC's.
But that's not the case.
When evaluating ETH, the market still focuses on specific metrics:
- Ethereum mainnet revenue;
- DeFi activity;
- Whether stablecoins and RWAs are settled primarily within the Ethereum ecosystem;
- Value flow from L2 to L1;
- ETH staking yield;
- Capital inflows into ETH ETFs;
- Competition from ecosystems like Solana, BNB Chain, and Base.
These are fundamentally the valuation logics for network assets, platform assets, and ecosystem assets.
BTC is different. It has no cash flow, no application ecosystem, and doesn't need to discuss network revenue. Its logic is simple: a 21 million supply cap, non-sovereignty, censorship resistance, digital gold. People might disagree with the narrative, but it's simple, clear, and easy to communicate.
ETH's narrative is far more complex. ETH serves as gas fees, staking assets, DeFi collateral, L2 settlement assets, and the infrastructure for institutional on-chain finance. While multi-functionality is an advantage, monetary premium usually requires a minimalist narrative.
Complexity benefits ecosystem development, but it doesn't necessarily help form a monetary premium like gold and BTC.
2. Legal Classification is Just a Ticket
The original article makes a key leap: because ETH might be legally recognized as a decentralized digital commodity, it should enter the valuation framework of top-tier monetary premium assets.
I find this deduction problematic.
What legal classification solves is: Can institutions hold it compliantly? Can it be traded compliantly? Can it be custodied compliantly? Can related products be developed compliantly?
What the monetary premium solves is: Is the global market willing to hold it as a long-term store of wealth?
These are two different questions.
Gold has a monetary premium, not because any single law classifies it as such, but because thousands of years of historical consensus, physical scarcity, central bank reserve demand, and geopolitical safe-haven attributes have formed a massive consensus.
BTC has a monetary premium, not because it can execute smart contracts, but because it is simple enough, pure enough, and behaves enough like "digital gold."
For ETH to achieve a monetary premium, regulatory classification alone is insufficient. It must also prove that global capital is willing to hold ETH as a long-term store of value, not just as important on-chain financial infrastructure.
There is still a significant gap between these two states.
3. DeFi Could Weaken ETH's "Only Interest-Bearing" Narrative
The original article highlights one of ETH's advantages: ETH can generate yield through staking, while BTC and gold cannot.
While this holds some truth today, the situation may change in the coming years.
With the development of DeFi and RWA, many assets will be tokenized in the future. Gold, treasury bonds, money market funds, real estate funds, revenue rights, commodities, and stock ETFs can all enter the on-chain financial system as tokens.
Once these assets are on-chain, they will also gain new capabilities:
- Can be used as collateral;
- Can be lent and borrowed;
- Can be used for market making;
- Can be combined into structured yield products;
- Can integrate with DeFi protocols;
- Can form a closed-loop on-chain capital flow with stablecoins.
Therefore, in the future, ETH will not be the only asset generating yield.
Tokenized gold integrated with DeFi can also generate on-chain yields. Tokenized treasury bonds and money market funds inherently have a base yield. Tokenized real estate funds and other RWAs can also generate cash flows.
At that point, the question will no longer be "ETH can generate yield, gold cannot."
The real questions will become: Who is better collateral? Whose volatility is lower? Whose yield source is clearer? Who has higher regulatory recognition? Who is more suitable for institutional balance sheets? Who is easier for global capital to hold long-term?
From this perspective, ETH may not have an advantage over tokenized gold, tokenized treasuries, or tokenized money market funds.
ETH's staking yield comes from network security mechanisms, not traditional risk-free returns. It carries protocol risk, validator risk, slashing risk, liquid staking protocol risk, regulatory risk, and price volatility risk.
For institutions, ETH staking is certainly a valuable feature, but it should not be directly equated to "better than gold."
4. Monetary Premium Belongs to BTC, Gold, and Tokenized Gold
I lean towards the view that, in the future, the monetary premium will primarily belong to BTC, gold, and potentially tokenized gold.
BTC's positioning is clear: digital gold.
Gold's positioning is also clear: the most important non-sovereign store of value in the traditional world.
If tokenized gold develops, the situation could be very attractive. It would inherit gold's historical credit while gaining on-chain liquidity, composability, and collateral capacity. In this case, gold's monetary premium wouldn't necessarily flow to ETH; instead, it might be further strengthened by tokenized gold.
This is not necessarily bad for ETH. These tokenized assets also need on-chain infrastructure and can be issued, traded, and collateralized on Ethereum or Ethereum L2s.
However, this means ETH is more of an infrastructure asset than a final monetary premium asset.
Infrastructure is certainly valuable. But infrastructure valuation typically reverts to usage metrics, revenue, network effects, and value capture, rather than directly analogizing gold's total market cap, real estate's monetary premium, or global reserve asset pools.
5. Ethereum's Value Capture Problem Remains Unsolved
The original article argues that CLARITY will widen the gap between ETH and other smart contract platforms, with other L1s potentially entering a second-tier valuation while ETH remains in the first tier.
This judgment also needs careful consideration.
The real world won't choose a blockchain solely based on US regulatory classification.
Different countries, assets, and institutions will choose underlying networks based on multiple factors:
- Cost;
- Performance;
- Compliance interfaces;
- KYC/AML requirements;
- Local regulatory attitudes;
- Ecosystem resources;
- Liquidity;
- Relationships with asset issuers and service providers;
- Whether a permissioned environment is needed.
Many RWA, stablecoin, and payment scenarios may not necessarily choose the Ethereum mainnet. They might opt for L2s, app chains, consortium chains, or other L1s that better suit local regulations and business needs.
More importantly, even if a lot of activity occurs within the Ethereum ecosystem, it does not guarantee that ETH can proportionally capture the value.
As we have seen in recent years, while L2s have expanded the Ethereum ecosystem, they also raise a question: once L2s scale, how much value actually flows back to ETH?
If a large volume of transactions occurs on L2s with decreasing fees, and the application layer and L2s themselves capture more user value, while the ETH mainnet only handles final settlement and security, then ETH's value capture capability remains to be proven.
One cannot assume that Ethereum ecosystem growth automatically means a synchronous increase in ETH value.
That's why I believe ETH's valuation must return to specific issues like network revenue, settlement demand, collateral demand, staking yield, and ecosystem value flow.
6. Using Ethereum ≠ Buying ETH
Another distinction needs to be made: institutions entering on-chain finance does not mean they will allocate ETH as a core asset.
Institutions might:
- Use the Ethereum network;
- Use Ethereum L2s;
- Issue tokenized funds;
- Use stablecoins for settlement;
- Use on-chain custody and compliant transfer tools;
- Use DeFi or permissioned DeFi;
- Indirectly access on-chain finance through service providers.
None of these require them to buy large amounts of ETH.
Just as companies heavily using cloud services don't necessarily buy the stock of the cloud service provider, institutions using blockchain infrastructure don't necessarily need to hold the underlying token long-term.
For ETH to transition from a "network being used" to an "asset held long-term," a clear value capture mechanism is required.
If this mechanism remains unclear, the market will continue to value ETH based on revenue, fees, staking yield, and ecosystem growth.
7. Grand Narratives Can't Sustain Valuations Anymore
In the previous cycle, the market was willing to assign valuations based on grand narratives.
"World Computer," "Internet of Value," "Global Settlement Layer," "Bedrock of Decentralized Finance" – these narratives were very powerful. Ethereum was undoubtedly the most important representative.
But the market has changed.
Investors are increasingly asking: Where is the revenue? Where are the users? Where is the value capture? Where is the real demand? Where is the regulatory pathway? Where is the closed-loop business logic?
As we have repeatedly emphasized in recent years, Web3 cannot remain merely a vision; it must ultimately return to fundamental values and basic business logic.
Can it make money? Can it provide a better user experience? Can it create real economic value? If these questions cannot be answered, even the grandest narratives will struggle to sustain valuations long-term.
This applies equally to ETH.
While it is certainly one of the most important Web3 infrastructures, to achieve higher valuations, the market may need to see:
- Renewed growth in DeFi;
- Recovery of mainnet revenue;
- Clearer value flow from L2 to L1;
- Real settlement demand for stablecoins and RWAs within the Ethereum ecosystem;
- Continued growth in ETH collateral demand;
- Institutions not just using Ethereum, but actually needing to hold ETH.
None of these can be automatically achieved through a single piece of legislation.
8. The True Significance of CLARITY is Fixing the Regulatory Discount
Therefore, I lean towards viewing the impact of CLARITY on ETH as reducing the regulatory discount, rather than unlocking trillions of dollars in monetary premium revaluation potential.
ETH has indeed faced regulatory uncertainty in the past. If US regulators more clearly recognize ETH's commodity nature, that would be a major positive.
However, this would transform ETH from a "network asset with regulatory tail risk" to a "network asset with clearer regulation."
This is already significant.
But it does not mean ETH automatically becomes a substitute for gold, BTC, or global reserve assets.
If the market continues to value ETH based on network revenue, staking yield, L2 value flow, DeFi activity, RWA settlement volume, and institutional usage, then ETH's valuation will remain constrained by fundamentals.
This isn't necessarily a bad thing. Good infrastructure assets deserve high value. But they are not equivalent to monetary premium assets.
9. My Stance on ETH
I still believe ETH is one of the most important assets in the digital asset industry.
Its long-term value stems from several factors: First, it is the most important open smart contract network.
Second, it is the key settlement layer for DeFi, stablecoins, RWAs, and on-chain finance.
Third, from a regulatory perspective, it is one of the most defensible decentralized infrastructures.
Fourth, it has accumulated long-term recognition from developers, applications, assets, and institutions.
Fifth, as Web3 enters large-scale commercial application, it










