

A Thousand-Billion M&A Double Kill, Giants' Better-Than-Expected Earnings Also Dive: Is Wall Street Starting to Nitpick?
1. The Indexes Held Steady, but AI Stocks Began Recalculating
On November 2, the U.S. stock market showed a striking divergence: index declines were not extreme, yet selling within the AI supply chain was quite fierce. The Dow closed up 0.41% at 51,983 points, the S&P 500 fell 0.51%, the Nasdaq fell 1.07%, and the Philadelphia Semiconductor Index fell 3.3%. Marvell closed down 12.72%, AMD fell 7.52%, Intel fell 8.8%, and Micron fell 5.78%.
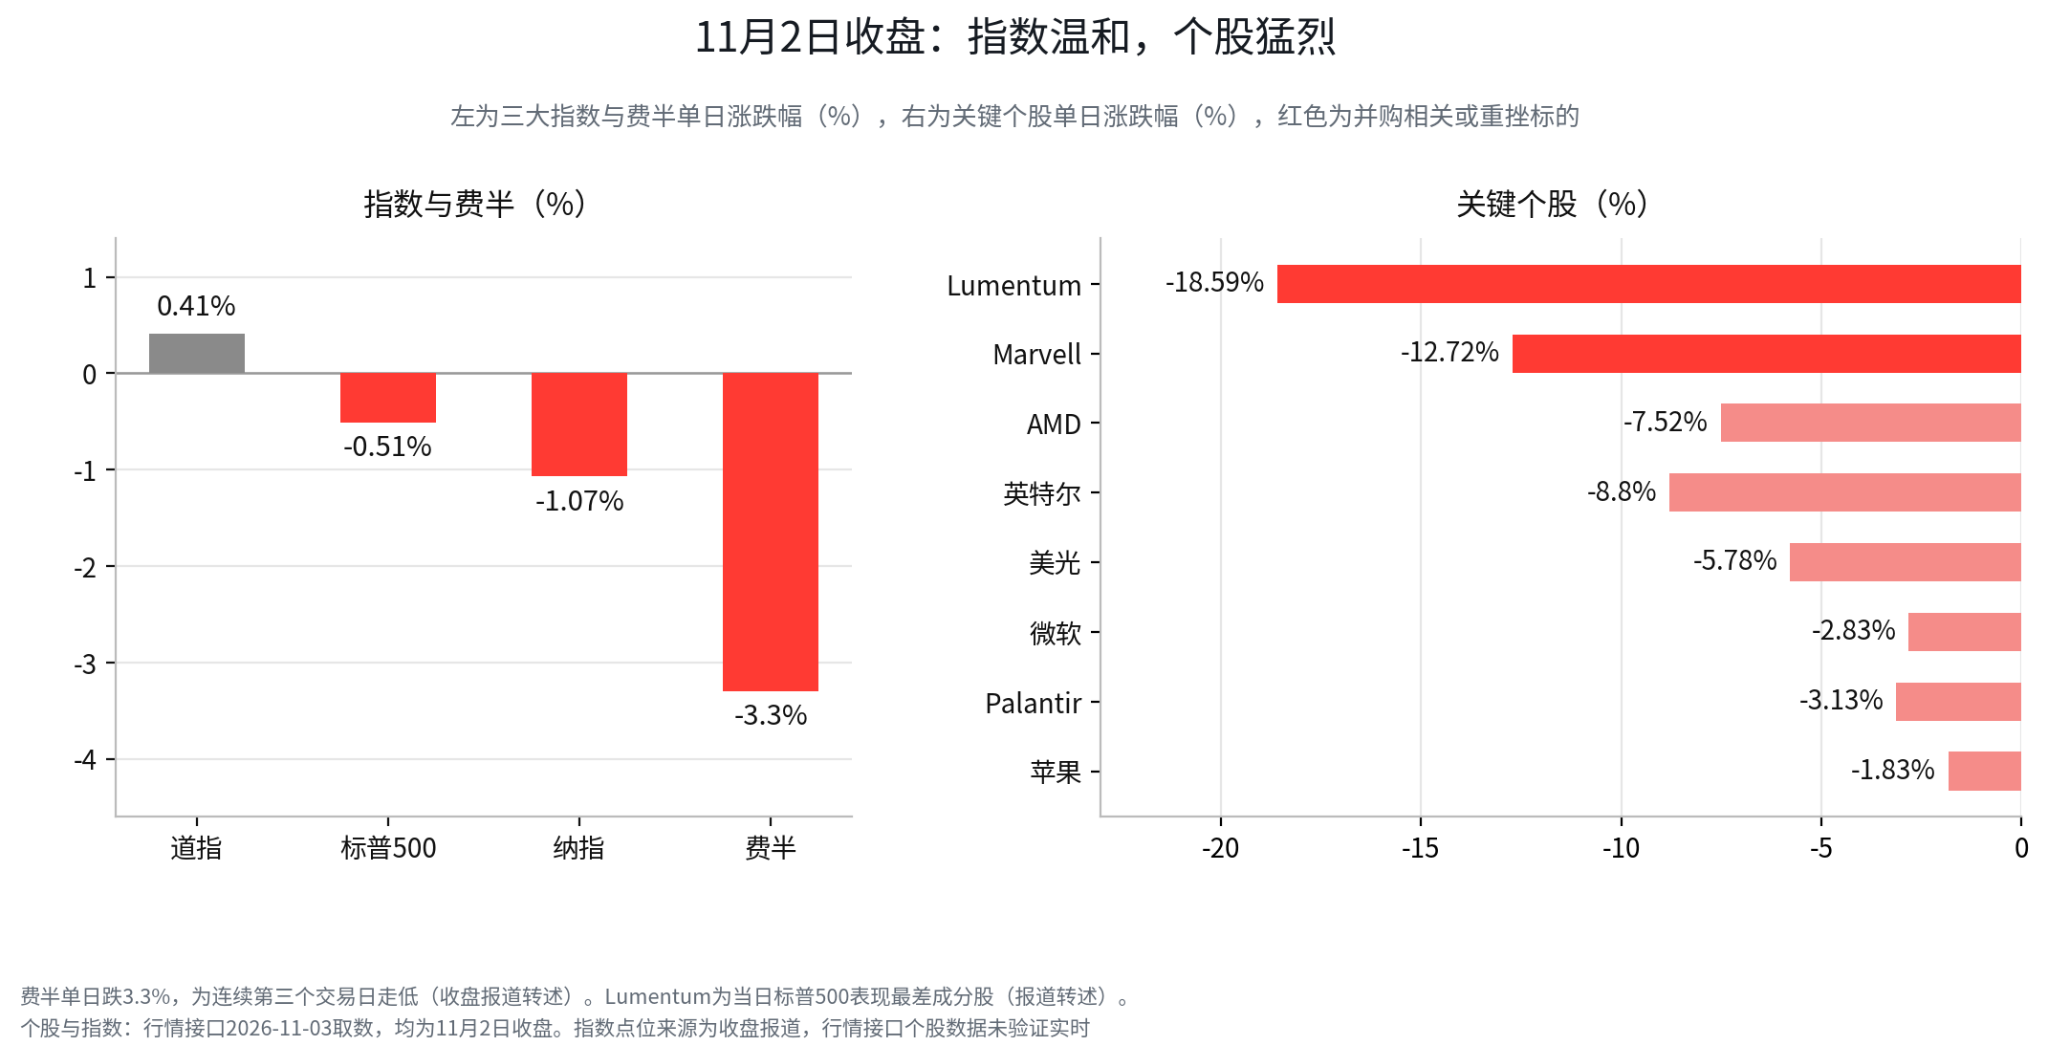
This does not mean the market suddenly stopped believing in AI demand. Microsoft's latest disclosed quarterly capital expenditure reached $45.2 billion, which, although below the market expectation of $51.7 billion, still grew about 30% year-over-year, and Microsoft's stock still closed down 2.83% that day. After several rounds of large-scale capital spending, investors are asking more specific questions: how much longer will investment keep growing, can orders be sustained, and can incremental revenue cover depreciation, energy, equipment, and R&D costs.
The Marvell and Lumentum merger has pushed this discussion to the forefront. It is not just a large transaction, but also a concentrated test of how the market reassesses the return on AI infrastructure investment.
2. $115 Billion for Optical Interconnect, and the Market First Asks Who Bears the Cost
According to the announcements from both parties, Marvell is acquiring Lumentum in an all-stock deal, with each Lumentum share exchanged for 4.5 Marvell shares, representing a premium of about 23.9% over the closing price before the deal rumors emerged on October 28, with an implied enterprise value of about $115 billion. After the transaction closes, Marvell's existing shareholders are expected to hold about 67% of the combined company, and Lumentum shareholders about 33%. The transaction still requires shareholder and regulatory approval and is expected to be completed in the first half of 2028.
From an industry logic perspective, this transaction is not hard to understand. Marvell provides high-speed electrical chips, including DSP and PHY, while Lumentum owns laser arrays and photodetectors. The merger of the two companies means further integration of the supply chain from electrical signal processing to optical signal transmission. Marvell disclosed a combined potential addressable market of about $550 billion (as relayed by reports), and Lumentum management previously said that capacity for some components has been booked into early 2029, with customers beginning to lock in orders further out.
But the industry logic holding up and whether the transaction price is reasonable are two separate questions. Marvell chose to pay the entire consideration with its own stock, so the premium Lumentum shareholders receive ultimately depends on whether Marvell's share price can hold up, while Marvell's original shareholders must bear the risks of equity dilution, integration execution, and synergies falling short of expectations. The transaction is not expected to be completed until the first half of 2028, meaning investors need to pay in advance for operating results more than two years out.
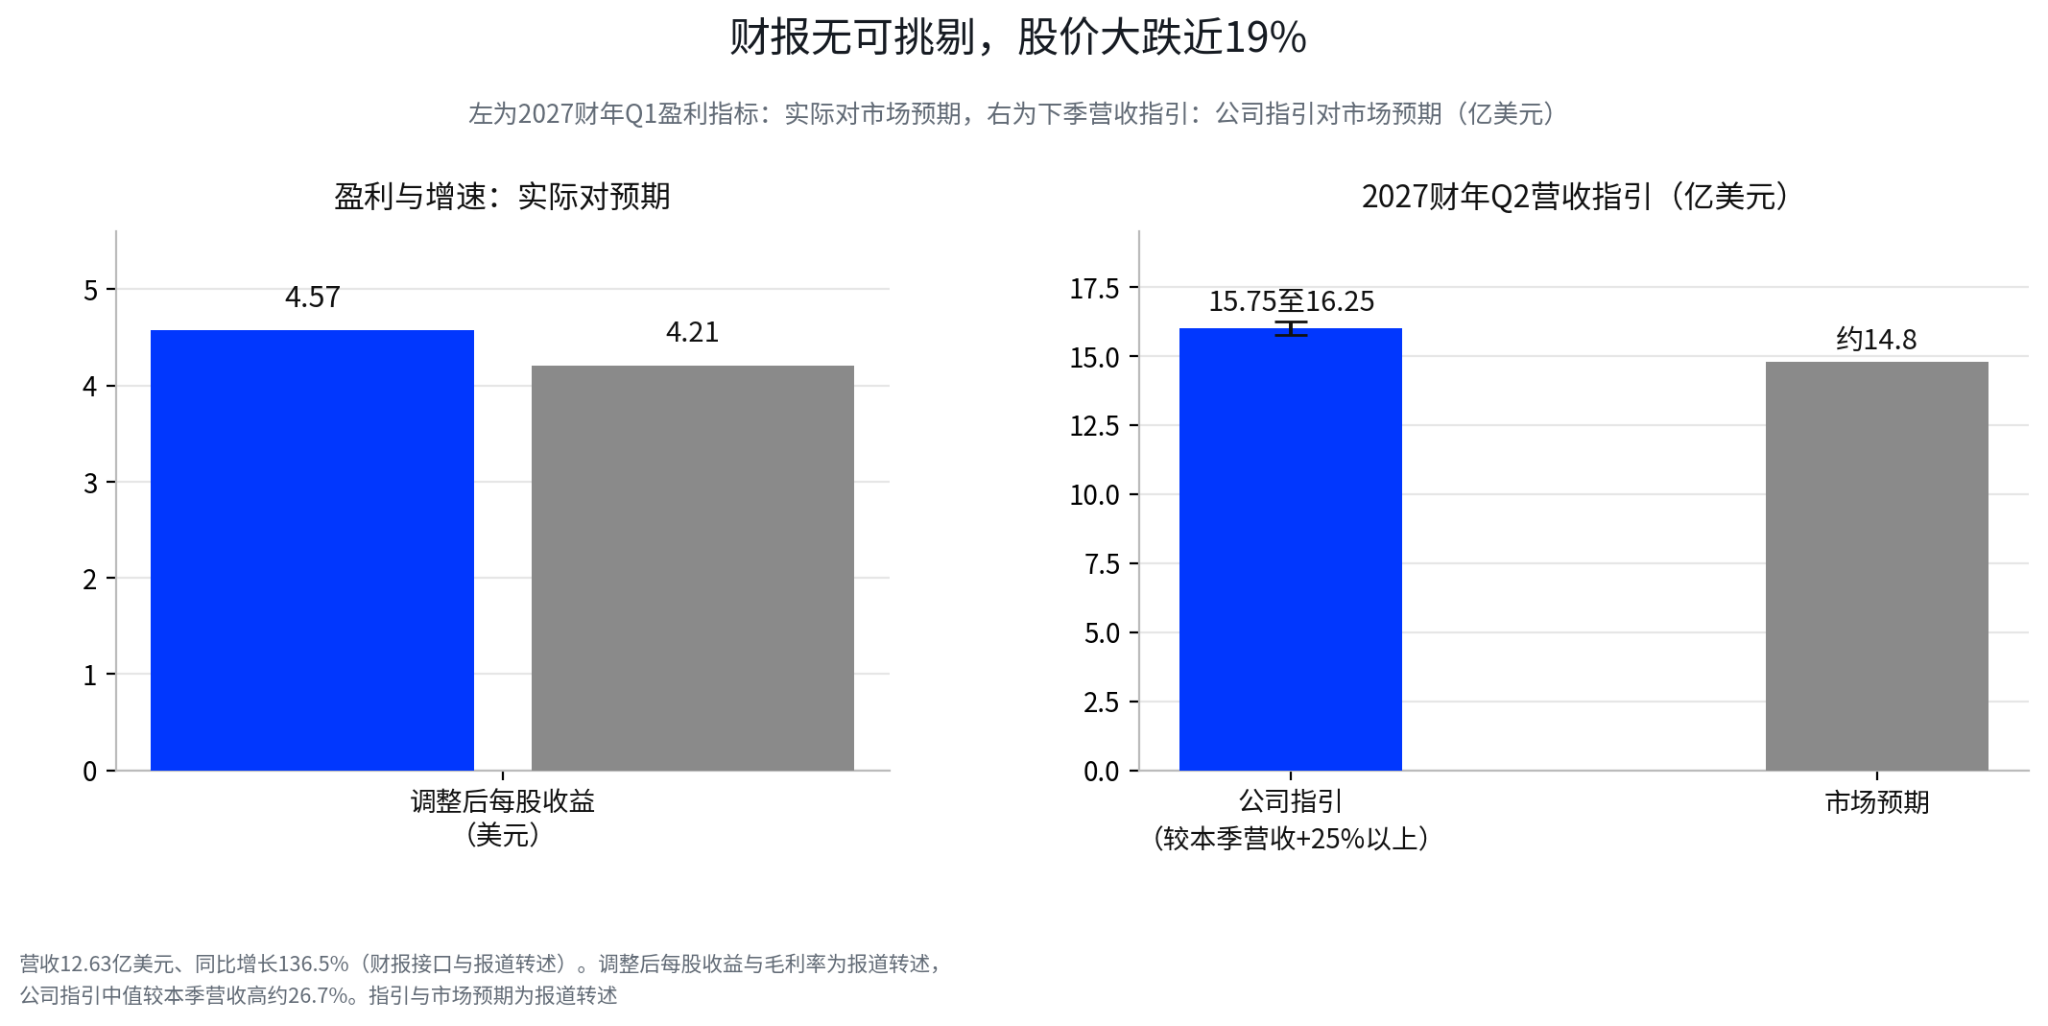
More importantly, Lumentum's reported financials themselves are not bad. Fiscal 2027 first-quarter revenue was $1.263 billion, up 136.5% year-over-year (revenue calculated from the financial report interface; the growth rate is as relayed by reports), adjusted earnings per share were $4.57, above the market expectation of $4.21, and adjusted gross margin was 53.2%, above the expected 51.3%. The company's revenue guidance for the next quarter was $1.575 billion to $1.625 billion, also above market expectations, and it disclosed new NPO/CPO project orders and more than $5 billion in purchase commitments.
A company with rapid revenue growth and earnings and guidance both better than expected closed down 18.59% on the day the transaction was announced. The focus of the market selloff is not Lumentum's current operating performance; what it cares about is the consideration shareholders ultimately receive after the transaction closes and the risks they will bear in the future.
The change in Marvell's own share price more directly reflects this repricing. From $251.65 at the close on October 28 to $171.41 at the close on November 2, the stock fell about 31.9% over three trading days. Because the transaction uses a fixed exchange ratio, the decline in Marvell's share price simultaneously lowered the value of the stock Lumentum shareholders could receive, and the originally promised premium quickly shrank. The transaction has not yet closed, but the market has already adjusted its price.
Market concerns are concentrated in three areas: dilution from all-stock payment, the long timeline requiring completion only in 2028, and whether synergies can truly be realized. The two parties proposed an annualized cost synergy target of more than $1 billion; if the two companies' operational overlap is limited, the room for cost savings may not be as large as the scale of the transaction suggests (as relayed by reports). Regulatory approval is also a variable: Lumentum currently still supplies Marvell's competitors, and the transaction includes a termination fee of up to $5.8 billion (as relayed by reports). The high termination fee itself shows that both parties are aware of how much uncertainty exists in the approval and integration window over the next two-plus years.
The most noteworthy aspect of this transaction is how much the market is willing to pay for long-term growth. Demand for AI infrastructure can continue to grow, but if companies need to achieve growth through large-scale stock payments, long-term integration, and high valuations, shareholders will demand higher return compensation.
3. Apple and Palantir: Good Results, So Why No Good Stock Price?
The merger transaction exposes the cost of capital allocation, while Apple's and Palantir's financial reports present the same change from the income statement and valuation sides: the market no longer looks only at how high a growth figure a company delivers, but also at what price was paid behind that growth and whether actual results exceeded the expectations already embedded in the stock price.
Apple's fourth-quarter revenue was $114.48 billion, up 12% year-over-year, above the market expectation of about $113.4 billion; earnings per share were $2.10, exceeding the expected $1.99 (revenue and EPS calculated from the financial report interface; expectations are as relayed by reports). iPhone revenue was $57.58 billion, up 17% year-over-year, and services revenue was $31.57 billion, a record high (as relayed by reports). Looking only at revenue and profit figures, this is a fairly strong financial report.
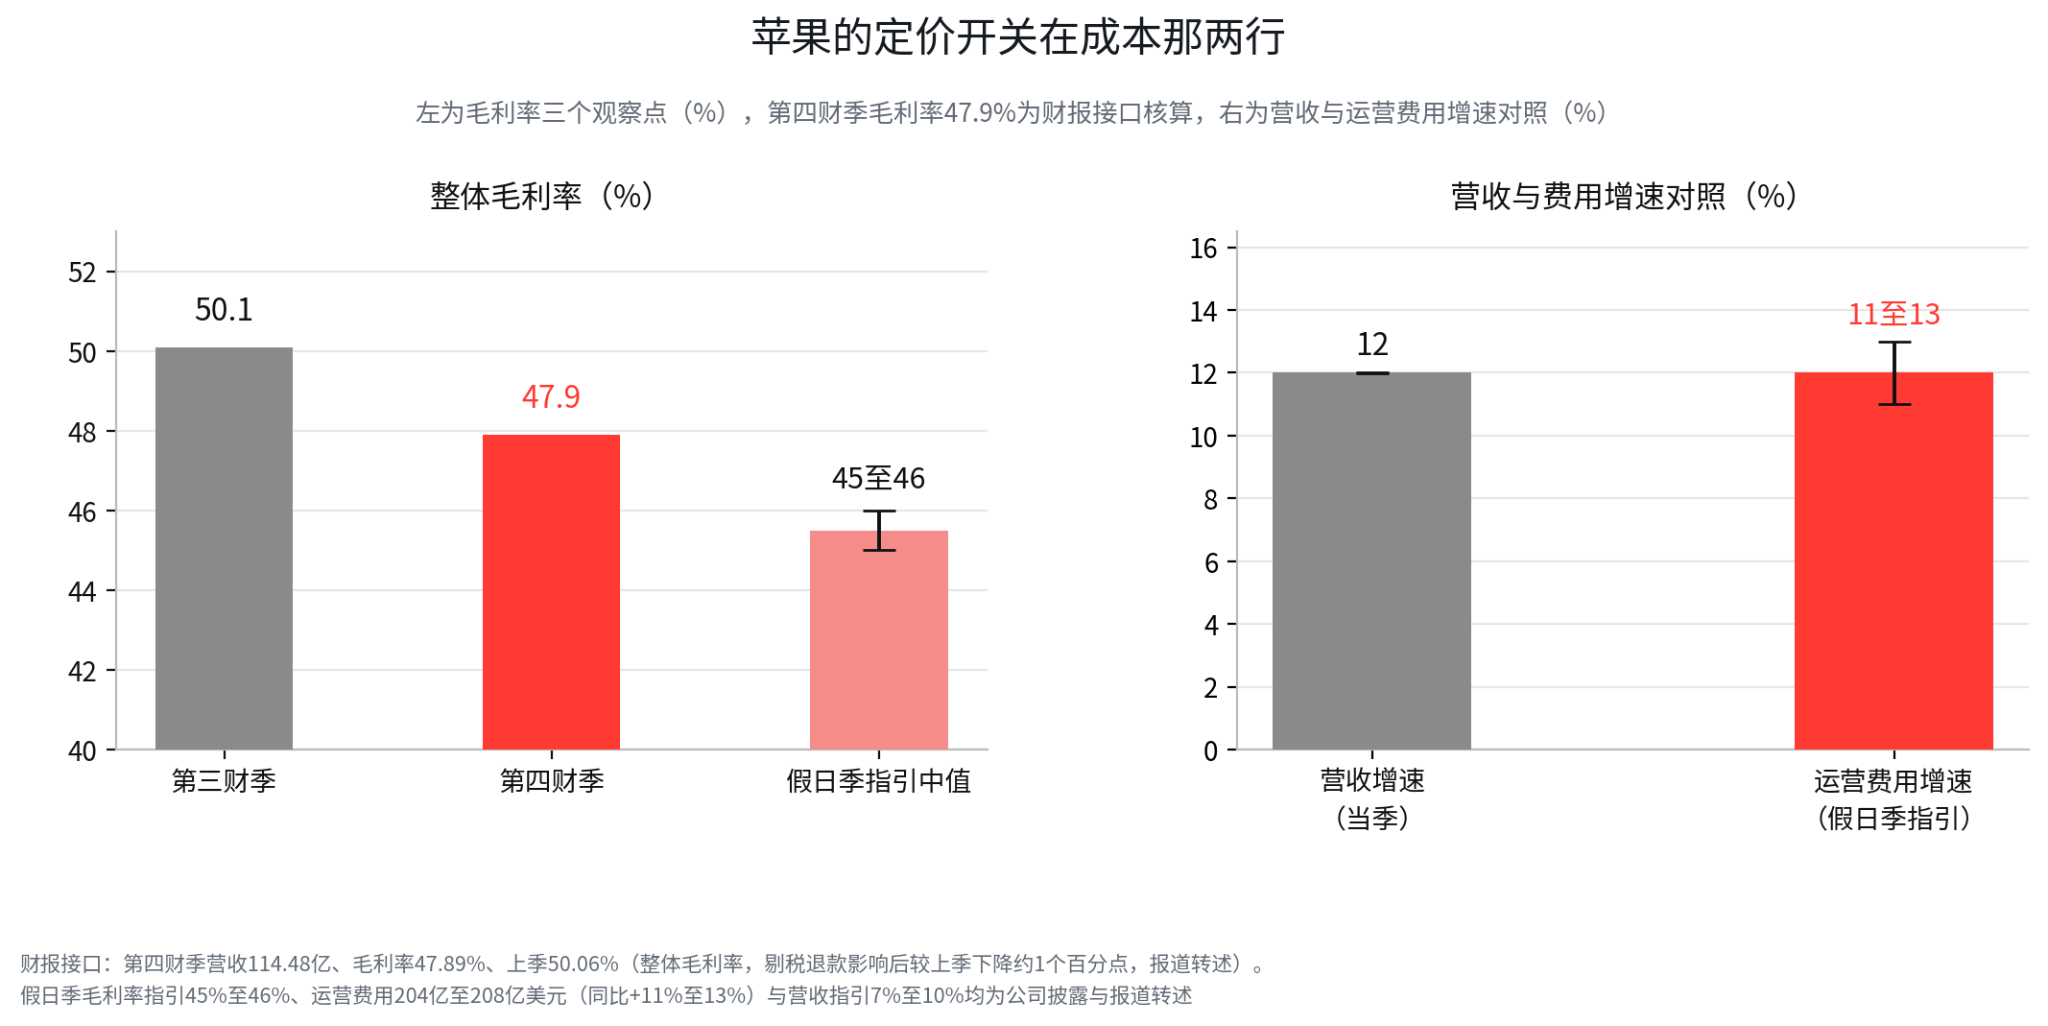
But the stock price did not give a corresponding reward. Apple closed down 1.83% on November 2, with market capitalization falling back to around $4.94 trillion, and fell more than 3% at one point after hours. Market focus centered on gross margin and expense guidance: fourth-quarter overall gross margin fell to 47.9% from 50.1% in the previous quarter, and the company expects holiday-quarter gross margin to fall further to 45% to 46%. At the same time, holiday-quarter operating expenses are expected to reach $20.4 billion to $20.8 billion, up 11% to 13% year-over-year, mainly driven by increased AI-related R&D investment (as relayed by reports).
This means Apple's revenue growth remains strong, but profit margins are being squeezed by costs. Holiday-quarter revenue guidance implies growth of 7% to 10%, while operating expenses are expected to grow 11% to 13%; if revenue growth cannot reaccelerate, expenses and storage costs could continue to compress margins. Apple does not need to invest huge capital to build data centers like cloud computing giants, but AI investment will still be reflected in its income statement through R&D expenses, memory chip costs, and changes in product mix.
For Apple going forward, the key observation points, besides iPhone sales, are more about whether gross margin can stabilize, whether storage costs will continue to rise, and whether AI investment can bring sufficient product and services revenue. For investors, revenue beating expectations is only the first threshold; whether margins can be defended determines the quality of this growth.
Palantir faces a different kind of pressure: costs have not suddenly deteriorated; the pressure comes from the market having already priced very high growth expectations into the stock.
The company's third-quarter revenue was $2.313 billion, up about 96% year-over-year; U.S. commercial revenue was $984 million, up 148% year-over-year; adjusted earnings per share were $0.44, above the market expectation of $0.41; and the company also raised its full-year revenue guidance to $8.530 billion to $8.534 billion. Looking only at the financial report, these figures are enough to show that the business is still in a high-growth phase.
But Palantir's stock turned lower after a brief after-hours rise, having already fallen 3.13% during the regular session. The pricing of high-valuation growth stocks depends not only on how fast growth is, but also on whether growth continues to exceed the threshold the market has already set. When investors have already paid a high valuation for rapid growth over the next several years, merely meeting or slightly beating expectations for a single quarter often only means previous optimistic expectations have been confirmed, rather than new upside emerging.

What Palantir needs to prove next is whether the rapid growth of its U.S. commercial business can continue and whether its international commercial business can keep up. Expense growth from hiring, product R&D, and market expansion also needs to be watched. For this type of high-valuation company, investors need to judge growth slope, margins, and valuation together; year-over-year revenue growth is only one piece of the puzzle.
What Apple and Palantir have in common is that the financial reports themselves did not show obvious shortcomings, but the market had already digested a considerable portion of the good news in advance. Companies must provide new evidence of growth to push their stock prices further upward.
4. AMD Takes the Baton: The Test Shifts from Chip Demand to the Delivery Curve
After the close on November 3, AMD will report third-quarter results. The market expects revenue of about $13.0 billion to $13.1 billion, up about 41.5% year-over-year, and earnings per share of about $1.95, up about 62.5% year-over-year. In the current market environment, simply beating these figures may not be enough; what investors really want to confirm is the shipment pace of MI450 chips and Helios racks, as well as the company's outlook for the data center business in 2027.
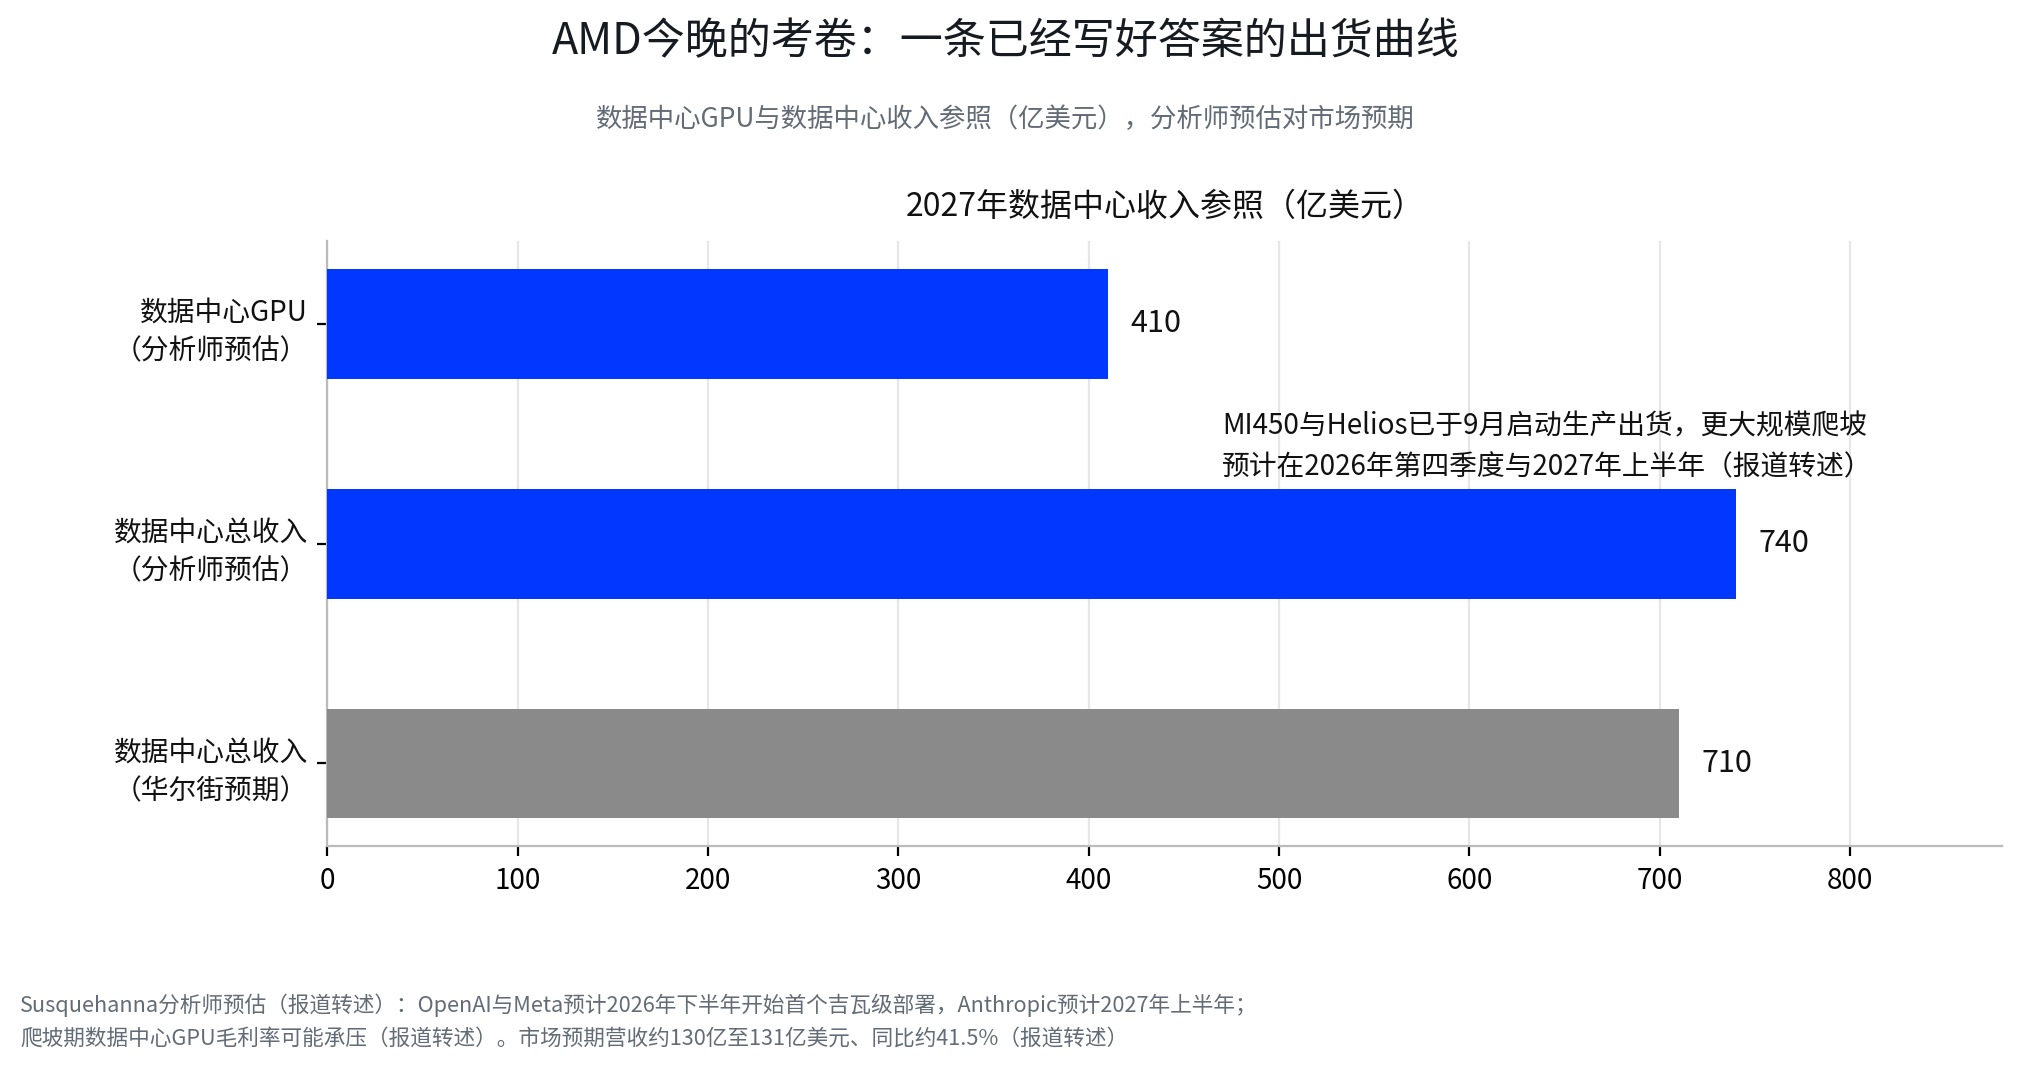
A Susquehanna analyst's estimate provides a reference path worth tracking: MI450 and Helios began production shipments in September, with a larger ramp expected in the fourth quarter of 2026 and the first half of 2027; OpenAI and Meta are expected to launch their first gigawatt-scale deployments in the second half of 2026, and Anthropic is expected to follow in the first half of 2027. The analyst expects AMD's 2027 data center GPU revenue to reach about $41 billion, with total data center revenue of about $74 billion, above Wall Street's expectation of about $71 billion.
However, this is still an analyst forecast, not realized order revenue. GPU shipment growth does not necessarily bring simultaneous margin improvement; product ramp, system delivery, customer deployment, and supply chain costs could all affect final profitability, and the analyst also cautioned that gross margin may come under pressure during the rapid expansion of the GPU business.
AMD closed down 7.52% in the previous trading day, as the computing power sector experienced consecutive corrections (market data interface). If the financial report can confirm the shipment pace of MI450 and Helios and provide a sufficiently confident 2027 data center outlook, the market may reassess AMD's growth potential as a second source of AI computing power. Conversely, if the shipment timetable is delayed or gross margin guidance is below expectations, the market may continue to lower its valuation of future revenue and earnings.
For AMD, the most important observation points tonight are verifiable delivery progress, customer deployment, and the margin path; management's description of the AI market opportunity is secondary information.
5. What to Watch Next in U.S. Stocks: From Chasing AI Concepts to Verifying Orders and Cash Flow
This market move does not mean the AI infrastructure investment cycle is over; what it changes is the market's requirements for different parts of the chain, and divergence begins there. Companies whose demand remains strong but which require large capital investment, and companies already able to convert orders into revenue and free cash flow, may receive different valuation treatment.
In the AI infrastructure direction, besides GPUs and chips, power, cooling, and data center supporting equipment are also worth continuing to track. The Marvell and Lumentum transaction shows that optical interconnect remains an important industry segment, but that does not make any optical communications company worth chasing at high prices. Investors need to distinguish between real orders, locked capacity, and long-term purchase commitments, and observe whether orders can be converted into revenue and whether capacity expansion will bring new capital expenditure and margin pressure.
Keep an eye on power and data center infrastructure suppliers such as Vertiv and Eaton. Vertiv's latest quarterly sales grew 61% year-over-year, organic orders grew 100% year-over-year, adjusted free cash flow reached $652 million, and the company also raised its full-year guidance. Eaton's second-quarter sales grew 21% year-over-year (calculated from the financial report interface at about 21.4%), Electrical Americas trailing orders grew 41%, and electrical backlog grew 43%. These indicators are more valuable for reference than pure AI concepts; they show that data center construction demand is being converted into equipment orders and corporate revenue.
But order growth and stock price upside are still two different things. What matters next is the pace of order conversion, the delivery cycle of backlog, gross margin, and whether valuation has already reflected future growth in advance. Post-earnings stock price reactions may also have already priced in order growth in advance.
For Apple, the focus should be on gross margin, storage costs, and services business growth. For Palantir, watch whether U.S. commercial revenue can maintain high growth and whether international business improves. Both companies have already proven business growth; the market's demands on them have escalated to continuously creating new expectation gaps.
For AMD, the most worth tracking are the mass production, shipment, and customer deployment progress of MI450 and Helios, as well as whether data center revenue growth can be converted into stable gross margin and cash flow. For Marvell and Lumentum, industry demand and merger risk should be viewed separately: optical interconnect demand can continue to grow, but the transaction completion time, stock exchange consideration, regulatory approval, and synergy realization are independent variables.
If you want to reduce the portfolio's exposure to a single earnings report or merger event, broad-based indexes can serve as a core position, while cash or short-dated Treasury-like assets can leave room for volatility during event weeks. When selecting stocks, rather than chasing the next hot AI narrative, it is better to prioritize companies with visible orders, stable margins, and free cash flow that can keep up.
The real watershed in this AI market cycle is how far into the future investors are willing to pay for growth and at what price. When merger premiums can shrink within days and financial reports that broadly beat expectations can still be met with falling stock prices, the market is already reminding investors: growth still matters, but the cost of growth, the time it takes to materialize, and cash returns are becoming more important pricing variables.
Disclaimer
Disclaimer: This content is for general information and market commentary only, based on public information available as of the time described in the article, and relevant market data, expectations, and probabilities may change as market conditions change. The views and investment strategies of third-party institutions, analysts, or other persons cited in the article represent only the views of the relevant third parties at specific times and do not represent BIT's views or recommendations. This article does not constitute investment advice, investment research, an offer, solicitation, or recommendation of any securities, investment products, or trading strategies, and should not be used as the basis for any investment decision. Financial markets involve risk; securities prices and market performance may fluctuate, and historical performance and past market trends do not represent or guarantee future results. Investors should independently assess relevant risks based on their own circumstances and seek professional advice when needed. BIT's Hong Kong stock trading services are not provided to Hong Kong residents or users in other restricted jurisdictions.