





Tonight the Fed's decision arrives, with the probability of a rate hike surging to 94%! What should you understand on FOMC night? How should four types of strategy-based ETFs be positioned for the FOMC?
At 2 a.m. tonight, global capital markets will face the most important macro judgment of the month—the Federal Reserve's monetary policy meeting. As of now, the rates market has pushed the probability of a 25-basis-point hike above 94%, with the federal funds rate range approaching 3.75% to 4.00%. Yet whenever such focal moments of global capital competition arrive, investors in the Asian time zone are always at a disadvantage. The 2 a.m. decision and the thrilling intraday battle of options strategies on individual stocks present a high threshold for ordinary traders. How can ordinary investors use strategy-based ETFs—drawing on the power of professional funds—to cope with the uncertainty of this meeting? This article explains the role and historical performance of these strategy-based instruments, and helps you sort out in advance the possible paths of market changes after the decision.
1. The FOMC Meeting: Which Three Things Should Ordinary Investors Understand?
Whenever there is a Fed meeting accompanied by a Summary of Economic Projections, what the market is really watching is not whether rates will be hiked that night or not, but the dot plot released along with the statement. Its official name is the FOMC participants' assessments of appropriate monetary policy. Each dot on the chart represents one participant's judgment of the midpoint of the target range for the federal funds rate at the end of each future year, accurate to one-eighth of a percentage point. These dots are published anonymously, so everyone can only see the overall distribution, not who specifically cast which vote.
The reason the dot plot matters more than the decision itself is simple. A single 25-basis-point hike only changes the cost of funds at one point in time, whereas the dot plot changes the market's expectations for the entire discount rate curve. For long-duration, highly valued growth assets in U.S. equities, their pricing is far more sensitive to where rates settle in the coming years than to whether there is a hike this month. Therefore, at such meetings, the real market move often does not happen in the second the statement is released, but in the hours or even days after the market has read the dot plot and recalculated the rate path.
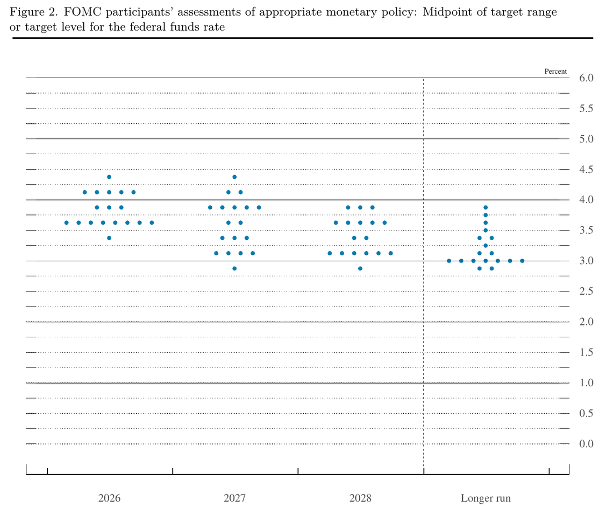
Chart: FOMC participants' assessments of appropriate monetary policy, released June 17, 2026. Source: Board of Governors of the Federal Reserve System, Summary of Economic Projections, June 2026, Figure 2.
Referring to the official dot plot baseline released by the Fed on June 17, there are three things that truly need to be understood tonight:
The first thing is to see which notch the median for the end of 2026 moves to on the dot plot. In June, the median forecast of 18 participants was 3.8%, with the densest cluster at 3.6%, totaling 8 participants, representing one more hike this year and then a pause. Around 3.9% there were 3 participants, around 4.1% there were 5, the highest was 4.4%, and the lowest was 3.4%. If after this 25-basis-point hike the dot plot still stays near 3.8%, it means most officials favor hiking once and then pausing to observe, which is a relatively dovish landing point, leaving room for long-end yields to fall. If it shifts up to around 4.1%, it means there is likely to be another 25-basis-point hike within the year, close to the baseline scenario the market is already pricing in. If it moves further toward 4.4%, the most hawkish tail from June, the market will need to start seriously trading a more sustained hiking path. The futures market is currently pricing in two hikes before year-end, while the June projection gave only one; whether the dot plot moves toward the market or stays put is itself a clear signal.
The second thing is to observe whether the entire 2027 curve shifts up together. In the June dot plot, the median forecast for the end of 2027 was 3.6%, 3.4% for 2028, and a longer-run neutral rate of 3.1%. This layer is actually more critical than how many more hikes there are this year. If the 2026 forecast dot is revised up but 2027 barely moves, it means the Fed is only doing a short-term re-tightening, simply pulling the pace of hikes forward. But if the entire path for 2027 and even 2028 shifts up markedly, what the market has to trade anew is a new normal of higher rates for longer. For U.S. equity valuations, the latter is far more damaging than a single 25-basis-point hike, because what it changes is the long-term neutral discount rate, not just this year's cash cost.
The third thing is to watch whether Warsh caps this hike at the press conference. The dot plot is static, the press conference is dynamic, and the market often sets the tone for the dot plot based on the tone of the press conference. During that half hour, focus on three things: inflation, oil prices, and the next hike. If Warsh emphasizes that future moves depend entirely on data and actively dampens market expectations for consecutive hikes, this could be interpreted as a dovish hike—that is, a hike lands but amounts to a declaration of a pause. Conversely, if he continues to stress inflation risks, energy prices, and that current policy is still not sufficiently restrictive of demand, the question the market truly trades will quickly switch to when the next hike will be. With Brent crude at $107, any phrase he uses about energy will be amplified in interpretation. And at the Jackson Hole meeting in August, he already said recent inflation readings had not yet sufficiently shown a return to the 2% target; combined with three officials voting for a hike at the July meeting, the market's psychological expectation for him to be hawkish is not low.
2. Market Review: S&P 500 and Nasdaq Overall Range-Bound
Over the past three weeks, U.S. equities have been broadly range-bound. The S&P 500 stayed in a narrow band from 7,580 to 7,700, less than 1.6% wide, oscillating repeatedly, until it broke down last week, falling to 7,580 at one point on Thursday, then reclaiming 7,620 on Friday and returning near its prior high, closing at 7,656.98. On September 14 it fell another 0.48% to close at 7,619.95, essentially back to where it started after a full round trip. The Nasdaq also showed no direction over the same period, falling 0.56% on September 14 to close at 26,186.41. Traditional defensive sectors fell collectively last week: health care dropped 3.55%, materials 2.84%, utilities 1.60%, and consumer staples 1.42%. The only sector to post a gain was energy, up 1.69%. When the reason for the decline is interest rates rather than economic growth, the old playbook of rotating into defensive stocks does not work.
Within the tech sector, there was sharp divergence. On September 14, the semiconductor ETF plunged more than 4% in a single day, while software and cybersecurity stocks rose against the trend, with CrowdStrike and Palo Alto Networks both posting gains. On the same day and under the same rate environment, AI hardware and software moved in opposite directions, meaning that even if you get the big picture right, you can still pick the wrong instrument.
Volatility also caught up. The VIX closed at 14.4 early in the month, the second-lowest level since December 2025. At that time, one-month 25-delta downside protection on the S&P 500 had fallen to its cheapest since December 2024, with skew at the flattest 1st percentile of the past year—almost no one was buying insurance against a decline. Last week the VIX rose to 15.84, and by September 15 it had returned to 17.96, up more than 5% in a single day, indicating that event premium was only bought back in the most recent trading sessions.
Putting these factors together creates an unfriendly combination for ordinary investors. The lack of direction in the index makes both long and short positions vulnerable, defensive sectors no longer resist declines so traditional rotation fails, intra-sector divergence lowers the margin for error in stock selection, and the deterministic event happens at 2 a.m. The options market is pricing an expected move of about plus or minus 1.1% for the night of the FOMC, equivalent to a 2.2% wide range, larger than the entire 1.6% range-bound band of the past three weeks. This is precisely why strategy-based ETFs exist: they do not solve the problem of direction, but improve the shape of investors' return distribution when direction is uncertain.
3. When Market Direction Is Unclear, How to Understand Four Types of Defensive Strategy ETFs
What is hardest to handle around the FOMC is not simply judging up or down, but facing multiple possible paths of evolution. The market may remain in high-volatility oscillation, may rebound after bad news lands, may see a clear correction, or may plunge first and then surge. In such an environment, the key is to think clearly about which outcome you fear most and what price you are willing to pay for stability.
Scenario 1: Long-term bullish on tech stocks, but worried about short-term volatility — QYLG
If you are long-term bullish on earnings growth at AI and large tech companies, but simply think short-term valuations are not low and the FOMC may amplify volatility, you do not have to leave the Nasdaq entirely.
In this case, you can choose to continue holding tech stocks while converting part of the short-term upside into option income. QYLG is a typical representative of this kind of Covered Call ETF. Its underlying remains the Nasdaq 100 Index, but it sells call options on roughly 50% of the stock portfolio. Investors retain relatively high Nasdaq exposure and convert part of future upside potential into option premiums in advance.
QYLG sits between QQQ and QYLD. QQQ fully participates in the rise and fall of the Nasdaq 100, QYLD uses a high coverage ratio and emphasizes option income more, while QYLG chooses about half coverage to balance growth and income. It is suitable for expressing a moderate view of being long-term bullish on tech but believing a one-way surge is difficult in the short term.
Historical performance shows its boundaries. In 2022, when tech valuations compressed, QQQ's maximum drawdown reached 35.12% in November of that year, while QYLG's maximum drawdown over the same period was 29.98%, occurring in October of that year. For full-year returns, QQQ was -32.58%, and QYLG was -26.27%. The premium buffer offset part of the loss, but did not change the essential nature of its high Nasdaq exposure. Using the S&P 500 as a benchmark, QYLG participated in 91.13% of the decline but only 89.80% of the advance. It can make declines slightly gentler, but it is not a true downside protection strategy. It will still see larger drawdowns in a deep bear market and may underperform QQQ in a strong bull market due to the cap from calls.
Scenario 2: Hard to judge direction, just want to temporarily reduce volatility in an equity portfolio — DIVO
If you have no strong preference on market direction, neither believe a bear market is imminent nor are sure tech stocks can surge, and simply want to reduce the volatility of an existing high-beta or tech position while staying in the stock market, DIVO is a representative strategy.
DIVO is an actively managed ETF that uses a strategy of high-quality dividend growth stocks plus tactical Covered Calls. It does not mechanically replicate an index, nor does it sell calls on the entire portfolio at a fixed ratio. The fund manager first selects about 20 to 25 U.S. large-cap stocks focused on profitability, cash flow, return on capital, and dividend growth, then tactically sells calls based on valuation, volatility, and individual stock short-term price action. Its sources of return include capital appreciation, corporate dividends, and option income. This active approach does not require abandoning the entire portfolio's upside just to generate option income. Stocks with limited upside can have calls sold on them, while those with greater potential are retained.
During the 2022 market correction, SPY's maximum drawdown reached 24.50% in October of that year, while DIVO's maximum drawdown was 13.72%, occurring in September of that year. For full-year returns, SPY was -18.18%, while DIVO was only -1.46%. During the 2018 correction, DIVO's maximum drawdown was 9.64%, with annualized volatility of about 9.41%, noticeably lower than the broad market. However, DIVO's largest drawdown since inception occurred in the March 2020 pandemic shock, reaching 30.04%, versus 33.72% for SPY over the same period. This shows that defensive stock selection plus tactical calls can reduce the slope of declines, but cannot provide complete immunity during a systemic crash. It is suitable for investors who want to turn high-volatility exposure into a more stable portfolio while retaining upside potential, but the cost is that active stock selection may misfire, and a portfolio of just over 20 high-dividend holdings may lag in an extremely strong bull market.
Scenario 3: Genuinely worried about a clear market drawdown — BSEP
If what you fear is a 10% or even larger deep correction in the coming months, Covered Calls alone are not enough, because premiums cannot strip the initial downside risk out of the return structure.
In this case, you can study Buffer ETFs such as BSEP. BSEP is a Defined Outcome strategy. It uses the S&P 500 ETF as a reference and pre-sets the return structure for a specific period through FLEX Options. Taking the period starting in September 2026 as an example, the outcome period is from September 1, 2026 to August 31, 2027, with an initial Buffer of 9% and an initial Cap of 19.75% (data before fees).
Investors give up the high bull-market returns above the Cap in exchange for a buffer against the first portion of losses. If the S&P 500 ultimately falls 5% over the full period, the loss is within the Buffer range. If it ultimately falls 20%, it can be simplified as the first roughly 9% being buffered, with losses beyond that range still borne by the investor.
Real bear-market data show that Innovator's same-series 15% buffer product PJUL (referencing SPY), announced in July 2022, fell 0.80% in the period ended June 2022, while SPY fell 11.87% over the same period; NJUL, which references QQQ, fell 6.76%, while QQQ fell 20.93% over the same period. BSEP, as the September series, has a buffer of 9%. To evaluate BSEP, one should not look at whether it outperforms the S&P 500 over the long run, but at whether the Buffer works when a decline occurs. If the market keeps surging, BSEP will likely lag SPY—that is the cost paid for buying protection. In addition, the Buffer and Cap are tied to the starting point, so buying midway requires referring to the remaining values at that time. For example, as of September 15, 2026, BSEP's remaining Buffer was 8.53% and remaining Cap was 20.68%.
Scenario 4: Worried about a decline, but not knowing when the risk will occur — HELO
If the risk does not occur within a preset one-year period, and the investor wants to stay in the stock market for the long term while always maintaining downside protection, HELO offers a corresponding solution.
HELO is an actively managed Hedged Equity ETF that uses a portfolio of U.S. large-cap stocks combined with continuous rolling laddered option hedges. It does not have a fixed one-year Buffer; instead, it simultaneously runs multiple groups of hedges with roughly three-month maturities staggered by about one month from each other, establishing new protection after expiry, thereby diversifying the timing risk of when protection is established, without needing to precisely predict which month a correction will occur.
HELO was launched on September 28, 2023. Its historical data is shorter than DIVO's and it has not experienced the major bear markets of 2008 or 2022. But during the post-listing correction periods, it has already demonstrated the characteristic of reducing drawdowns. Its maximum drawdown was 3.60% in 2023, 4.16% in 2024, 10.89% in 2025, and 5.76% year-to-date in 2026, with the largest drawdown since inception at 10.89% in April 2025. Its annualized volatility is about 6.89%, its Beta relative to the S&P 500 is about 0.49, and its downside capture ratio is about 59.11%, meaning that for every 1% the broad market falls, it falls about 0.59%.
This validates its design goal of reducing drawdowns during ordinary correction periods, but its performance in a severe bear market still awaits testing with a larger sample. HELO is suitable for investors who want to hold stocks for the long term while keeping the portfolio continuously hedged, and the cost is likewise the option protection expense and lower returns in a strong bull market.
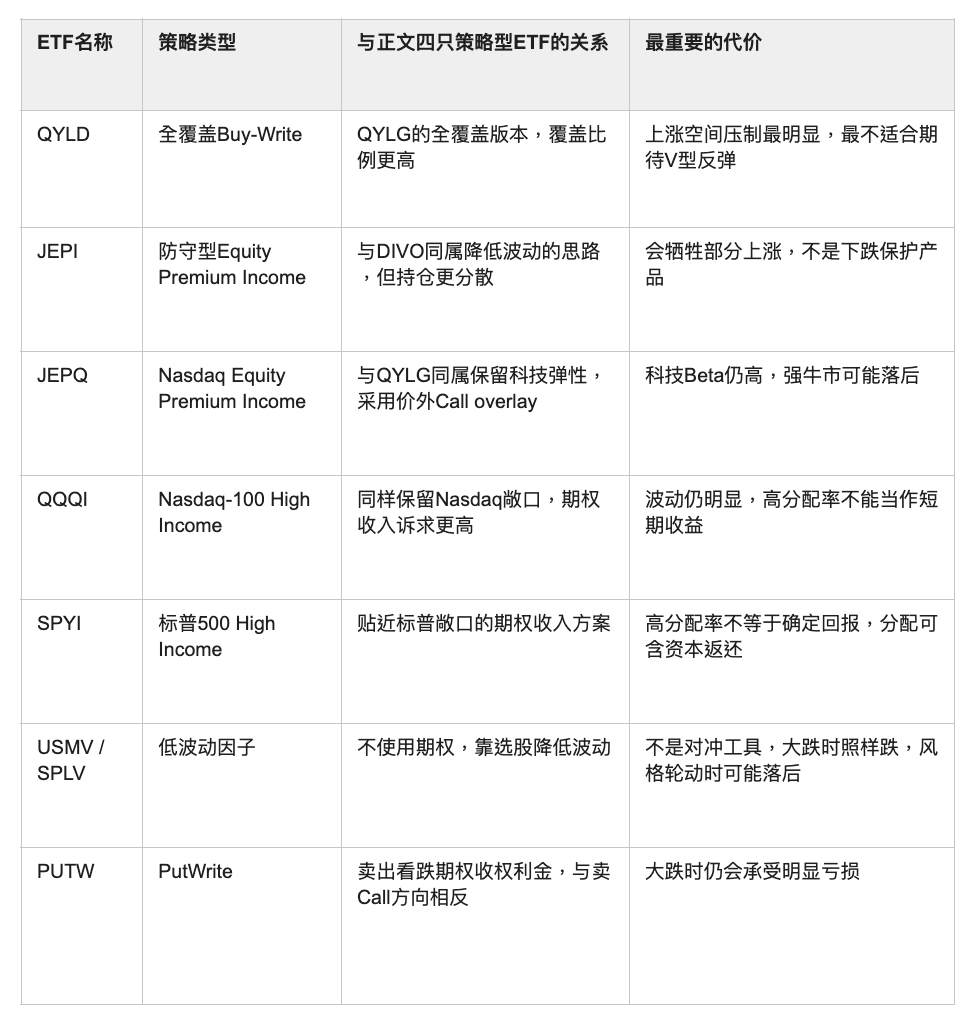
List of other related strategy ETFs:
Risk warning: The market data, Fed policy expectations, and historical performance of various strategy ETFs described in this article are compiled from public sources and are for reference only, not constituting investment advice. Historical performance does not represent future results, and options and structured products are subject to risks including expiration, liquidity, and loss of principal. Investors should make independent judgments based on their own risk tolerance and consult professional investment advisers when necessary.










