

Without Jensen Huang, how much would Nvidia be worth?
TL;DR
- Stifel has made a leadership transition its base case, cutting its Nvidia price target from $315 to $205 while maintaining a Buy rating.
- The revision falls mainly on the valuation multiple, with Stifel lowering its FY2028 forward P/E from 20x to 13x, while still expecting near-term results to modestly beat expectations.
- Dan Ives and Gene Munster previously estimated that Jensen Huang's departure could shave 20% to 30% off Nvidia's valuation, but at the time put the probability of departure at only 10% to 15%.
- With reports of a removal and succession search emerging, the earlier judgment that "departure risk is already priced in" needs to be revisited.
- TIKR calculates that, with earnings expectations unchanged, a 20% to 30% discount would compress Nvidia's forward P/E to roughly 10x to 12x.
- If subsequent export restrictions hit sales already included in forecasts, the market would also need to cut earnings estimates, putting both the multiple and earnings under pressure at the same time.
Jensen Huang's signature leather jacket is becoming a metaphor on Wall Street for the debate over Nvidia's valuation.
On November 10, Scott Galloway said on the Pivot podcast that the AI industry that night seemed to be "held up entirely by a leather jacket." As Nvidia's board launches an independent investigation into Huang, investors are starting to price a scenario rarely discussed seriously in the past—if the founder leaves, how much is Nvidia worth?
Some analysts' initial judgment was that the valuation could fall 20% to 30%. Brokerages then began adjusting their price targets. On November 12, according to Investing.com, Stifel cut its Nvidia price target from $315 to $205, a reduction of about 35%, while maintaining its Buy rating.
As of the time of publication, Nvidia had not announced any leadership change. But in Stifel's valuation framework, a management transition has already become the base case.
Jensen Huang's value is starting to show up as a P/E discount
Stifel's revision offers a concrete set of numbers for "how much is Jensen Huang worth."
The firm uses an FY2028 estimated earnings per share of $15.65, and lowered the P/E multiple used to calculate its price target from 20x to 13x. Under this approach, a 13x P/E corresponds to about $203, close to the new $205 target.
The P/E ratio reflects how much investors are willing to pay for each dollar of earnings. When earnings forecasts are broadly unchanged, a lower multiple means investors have less confidence in future growth and are willing to pay less.
Stifel remains relatively positive on Nvidia's near-term operating performance. The firm expects the company's FY2027 third-quarter results, due November 17, to modestly beat expectations, with supply still the main constraint on growth and room for upward revision to FY2028 earnings forecasts. At the same time, the choice of successor, the timing of the handover, whether key executives will stay, and how sales channels and export compliance arrangements will be adjusted all add uncertainty to long-term growth.
Other firms are also reassessing this risk. According to Investing.com, Bernstein downgraded Nvidia from Outperform to Market Perform and cut its price target to $200. Morgan Stanley removed it from its top picks list but kept its Overweight rating and $300 price target. The trade-offs firms are making between earnings and valuation have already diverged noticeably.
Huang's importance shows first in how Nvidia is organized. Robert Cyran, a Reuters Breakingviews columnist, noted that more than 60 people report directly to Huang at Nvidia, with four executives below him of equal standing. This structure, built around the founder, means a successor would need to take on technical judgment, internal coordination, and client communication all at once, making an emergency handover even harder.
External business relationships also test the successor. Major customers such as Microsoft, Amazon, and Google continue to buy Nvidia chips and are also motivated to develop cheaper in-house products. Huang raises the cost of switching suppliers by expanding supporting software and hardware, while building financing partnerships with firms such as Apollo and Blackstone to help customers fund chip purchases. Cyran argues that investment and financing support for smaller customers also helps broaden the buyer base and limits the bargaining power of a few large customers.
This arrangement ties product competitiveness, customer financing, and order growth together. Whether a successor can sustain these partnerships will shape investors' views on future revenue and margins, and determine how much valuation premium Nvidia can retain.
The 20% to 30% hit depends on the probability of departure
Before Stifel adjusted its price target, Dan Ives and Gene Munster had already tried to quantify the impact of Huang's departure.
Dan Ives of Yorkville Ives & Co. said on November 10 that if Huang were removed as chief executive, Nvidia's company and stock value could fall 25% to 30%. At the time, he estimated the probability of that happening at about 15%.
Gene Munster of Deepwater Asset Management put the impact at about 20%. He believed the stock price at the time may have reflected roughly a 25% departure probability, while his own estimate was 10% to 15%.
TIKR ran a simple probability-weighted calculation on this basis. Using Ives's judgment, a 25% to 30% valuation loss multiplied by a 15% probability translates to an overall valuation impact of about 3.75% to 4.5%. Using Munster's judgment, the impact is about 2% to 3%.
Based on these assumptions, TIKR argued in a November 11 article that the decline over two consecutive trading days may have already priced in most of the departure risk.
But that conclusion depends heavily on when the news was published.
Subsequently, The Wall Street Journal reported that the board was preparing to remove Huang, while Bloomberg reported that the company had hired a search firm and was considering appointing an interim chief executive. By the time Stifel issued its latest assessment, a leadership transition had entered its base case. The earlier 10% to 15% probability assumption therefore needs to be reassessed.
If investors see a departure as increasingly likely, the risk discount the current stock price needs to reflect will widen, even if the estimated magnitude of the post-departure valuation loss stays the same. Judging whether risk is fully priced in requires estimating both the probability of departure and the actual impact of a management change on company value.
With earnings estimates unchanged, Nvidia could fall to a 10x to 12x P/E
TIKR believes Nvidia's valuation still has support, based on market expectations for its earnings growth.
According to consensus estimates cited by TIKR, Nvidia's adjusted earnings per share will rise from $9.32 in the fiscal year ending January 2027 to $21.41 in the fiscal year ending January 2029, more than doubling over two years.
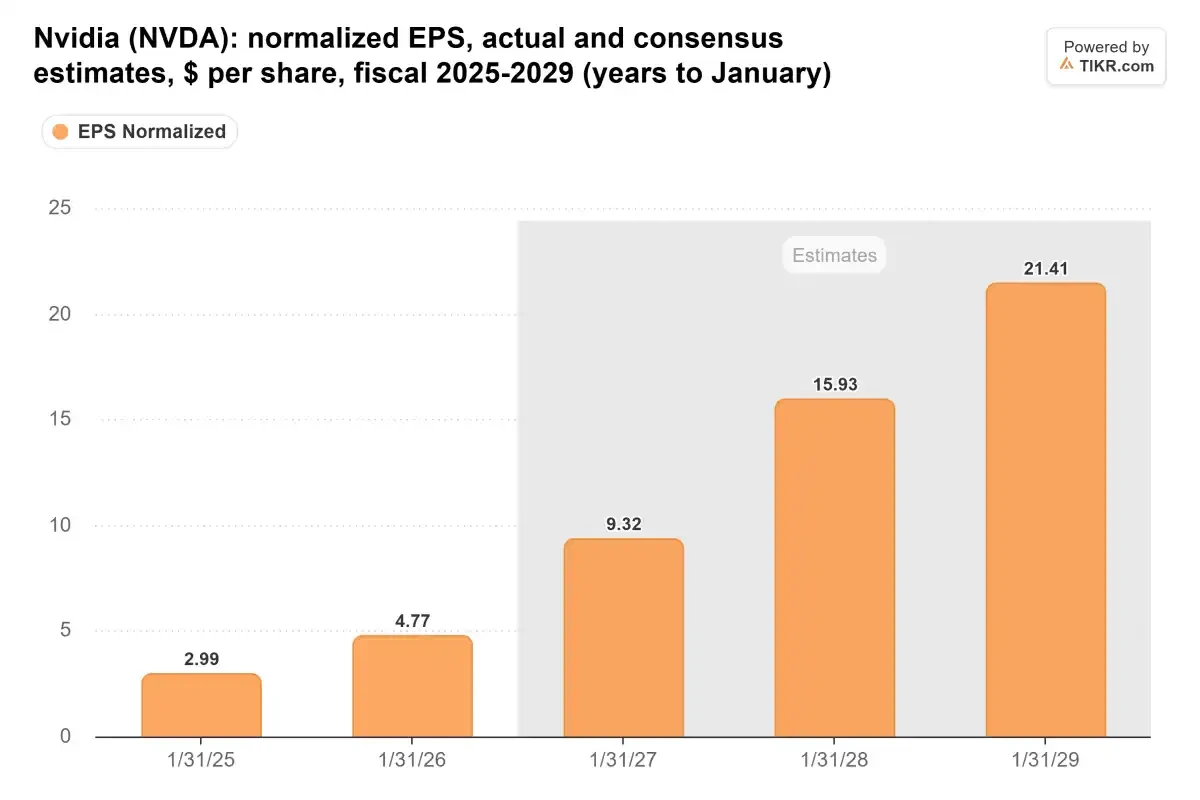
Nvidia adjusted EPS for fiscal 2025-2029, in US dollars. The gray area represents market consensus.
TIKR data shows that on November 9, Nvidia's forward 12-month P/E was about 14.8x, at a low over the past three years and below the roughly 30.1x average over the same period.

Nvidia's forward 12-month P/E over the past three years; the latest value in the chart is 14.75x.
If earnings forecasts hold and the stock price takes a 20% to 30% discount on this basis, the corresponding P/E would be about 10.4x to 11.8x. This is what TIKR means when it says "without Jensen Huang, Nvidia could become a 10x to 12x P/E stock."
This calculation uses the stock price and earnings expectations at the time. As prices and market judgments change, the corresponding multiples will change too. In addition, TIKR uses forward 12-month expected earnings, while Stifel uses FY2028 expected earnings, so the two valuation approaches differ.
Both calculations reflect that the market still expects Nvidia's profits to keep growing, but is reconsidering how much it should pay for those profits. An unclear successor, management stability, and strategic continuity could all weigh on the valuation multiple.
How much of this discount ultimately persists depends on whether Nvidia can present a credible handover arrangement and whether the successor can maintain product execution, customer relationships, and financing partnerships.
If earnings estimates are also cut, the re-rating would deepen further
The above calculations share one common premise—that the profits in analyst forecasts can be delivered.
TIKR notes that if a subsequent review leads to tighter export rules and affects sales already included in forecasts, analysts would need to cut EPS estimates. Price targets could then come under pressure from both lower earnings and multiple compression at the same time.
Nvidia's previous guidance already assumed no data center computing revenue from China. Therefore, the impact of future policy needs to be traced to specific customers, regions, and sales channels, to see whether new restrictions touch existing revenue forecasts.
The November 17 earnings report will provide a test. The company previously guided quarterly revenue of $108 billion, plus or minus 2%. Stifel expects actual results to modestly beat expectations, and investors will also focus on forward growth guidance and management's commentary on supply, customer demand, and leadership arrangements.
"How much is Nvidia worth without Jensen Huang" still depends on two sets of variables. If the company continues to deliver earnings growth, the market will mainly adjust the P/E it is willing to pay; if management changes further affect business execution and order expectations, earnings forecasts could also face downward revisions.
Whether the succession arrangement can stabilize the core team, whether product plans can proceed on schedule, and whether customers can continue to secure funding to buy computing power will determine whether the discount Wall Street is now assigning is compensation for transition-period risk or a more lasting valuation adjustment.