

2027 "Super Dollar"?
Original author: Zhang Yaqi
Original source: Wallstreetcn
The AI boom is reshaping global capital flows. The dollar hovers at elevated levels, but its fragile support structure leaves the super-dollar outlook full of uncertainty.
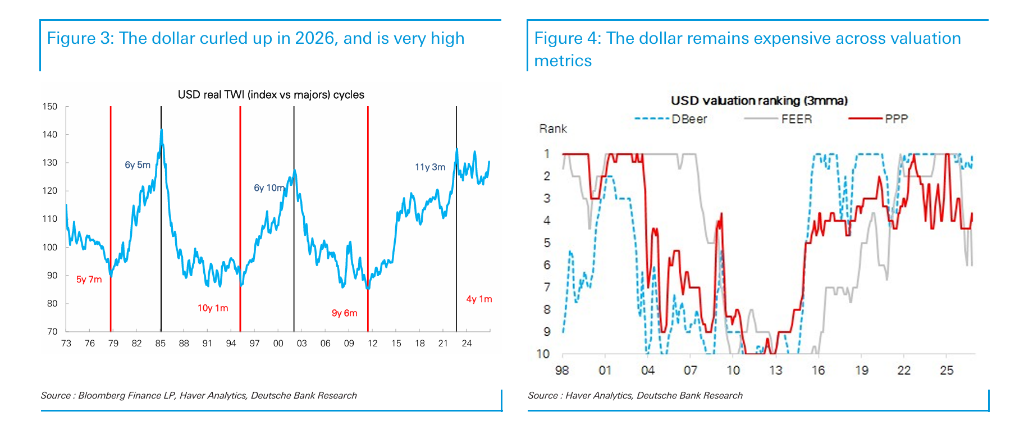
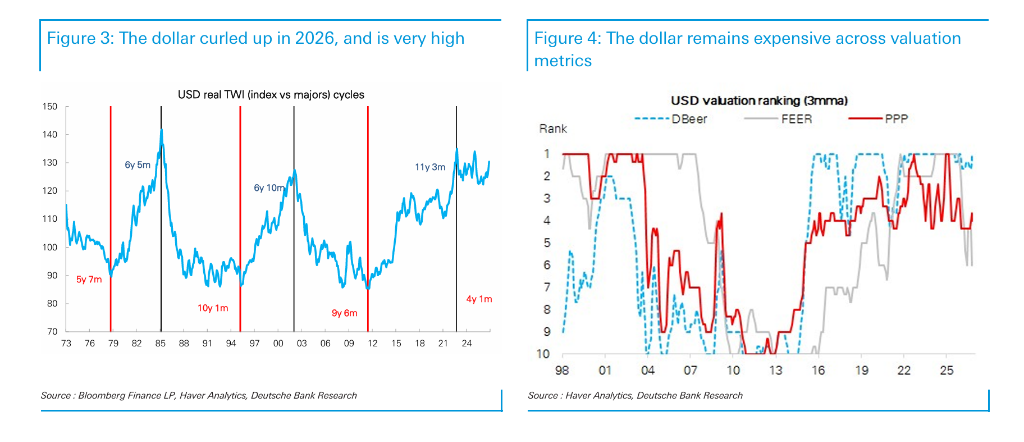
According to Wind Trading Desk news, Deutsche Bank has sharply raised its 2027 dollar forecast in its latest FX outlook report, acknowledging that its previous call for a weaker dollar has fallen flat. The AI boom has pushed up US real rates, attracted massive equity inflows, rekindled inflation pressures, and prompted the Fed to turn hawkish—together forging the current "AI dollar" regime. The dollar is now more than 20% above its four-year average and ranks among the most expensive G10 currencies on all three fundamental valuation metrics.
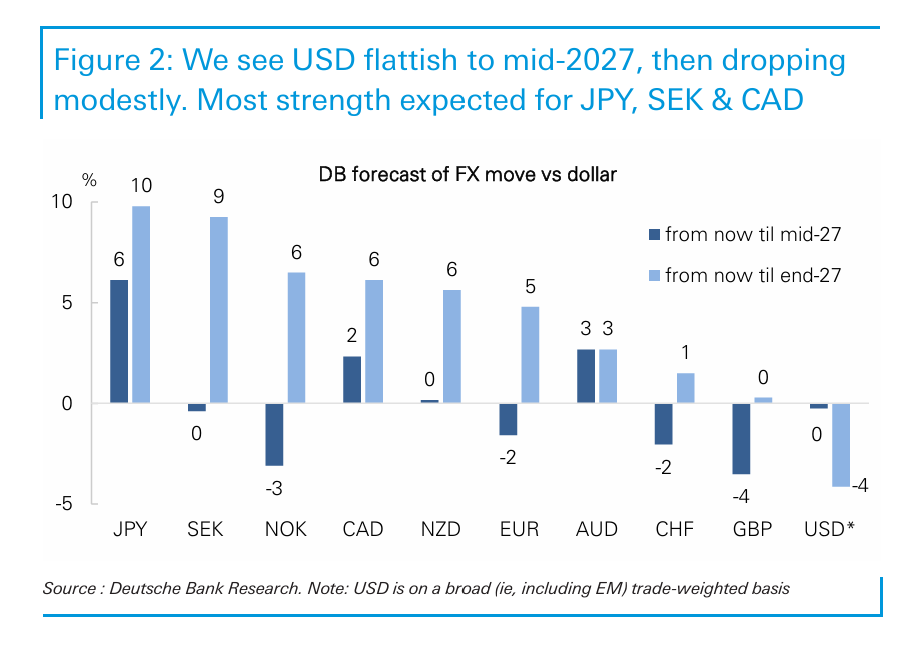
Deutsche Bank expects the dollar to extend its strength in the first half of 2027, post a modest pullback in the second half, but remain elevated overall. The report also warns that the dollar's dependence on the AI capex cycle is deepening. Should the market significantly cut its expectations for AI returns, the dollar's two supporting pillars—US real rates and equity inflows—would collapse in tandem, exposing the dollar to substantial downside risk.
AI Boom Underpins "Dollar Exceptionalism"
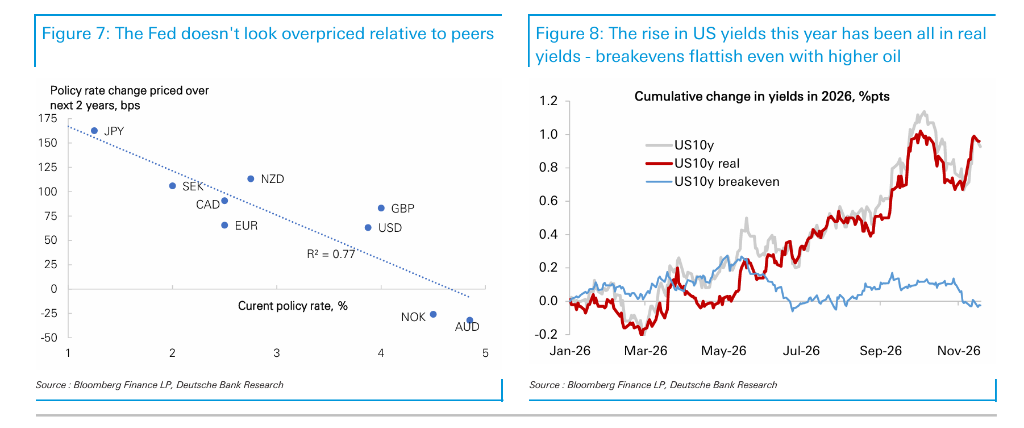
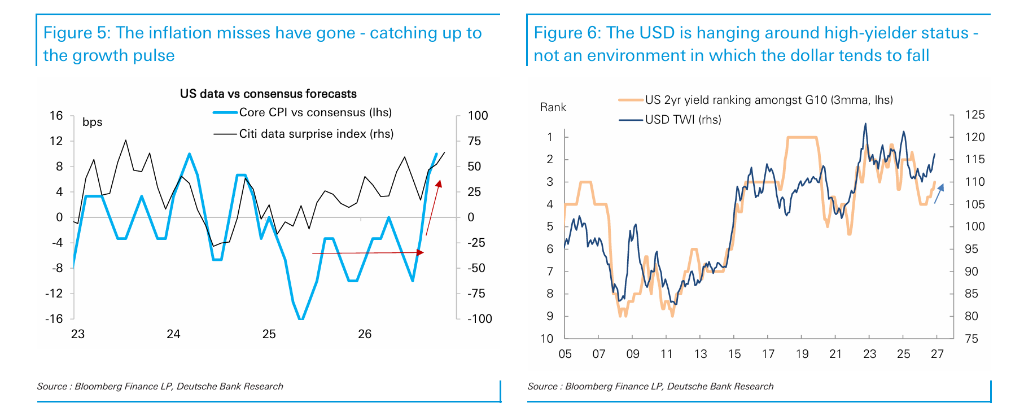
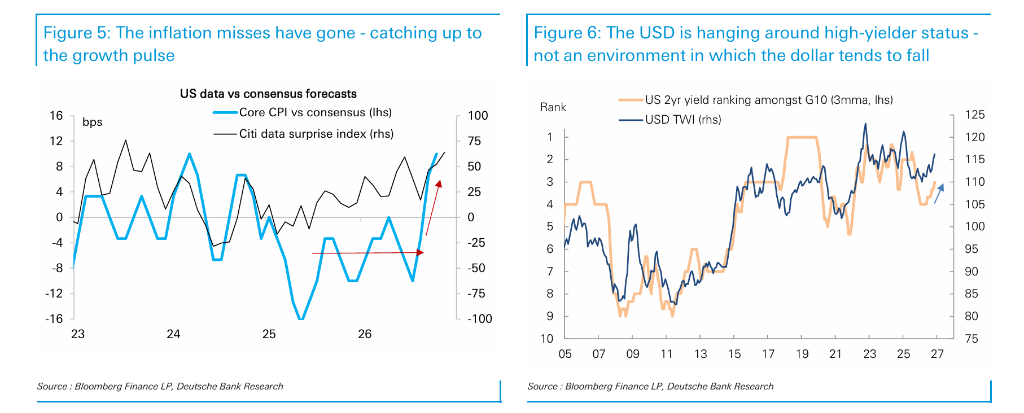
The core driver of dollar strength comes from within the US and could persist or even intensify in the near term. US inflation has re-accelerated over the past few months, with core PCE expected to breach 3%, driving a repricing in rates markets and pushing the dollar back into the top three highest-yielding G10 currencies—a status it had briefly ceded at the end of 2025. Deutsche Bank data shows that historically, the dollar has rarely entered a downcycle when offering high yields.
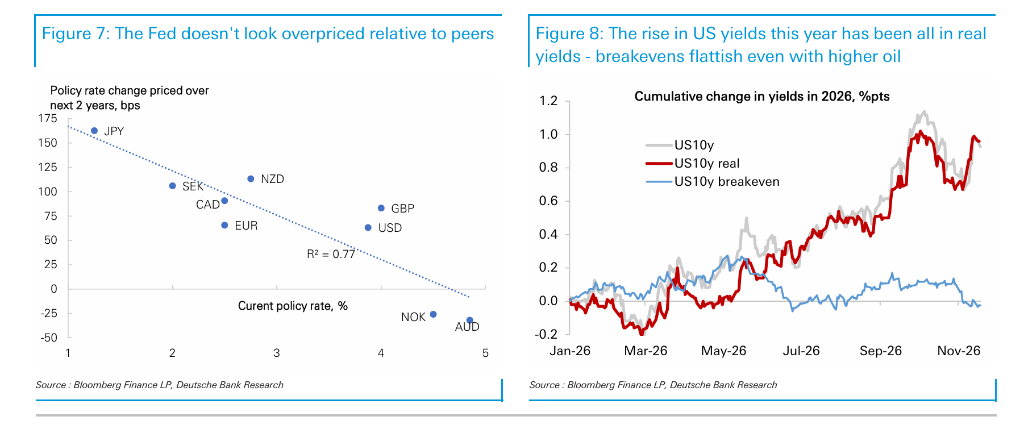
Rising real yields have simultaneously lifted US neutral rate expectations by about 50 basis points this year, while the euro area has remained virtually unchanged over the same period. Meanwhile, US GDP growth expectations have returned to the top of the G10, capex growth is roughly double that of other economies, and the AI-driven capacity expansion cycle lays the groundwork for productivity gains—all providing a positive incentive for the currency market.
Equity Inflows Dominate, Fixed-Income Flows Show Signs of Diversion
On the capital flow front, the US remains the core magnet for global equity investment. Foreign inflows into US equities have surpassed $1 trillion per year, becoming the primary source of financing for the US external deficit, and such flows typically carry low hedge ratios, providing a more direct boost to the dollar.
However, fixed-income flows are quietly shifting. Deutsche Bank data shows that US bond inflows have slowed, while bond inflows into other G10 markets such as Canada and Japan have rebounded significantly, shaking the "There Is No Alternative" (TINA) market narrative. FX reserve managers have also been steadily increasing allocations to other smaller currencies over the past year and a half. This trend warrants vigilance—if the diversification value of US dollar assets continues to decline, upward pressure on hedge ratios will increase accordingly.
High Valuations and Twin Deficits Pose Medium-Term Risks
The dollar's medium-term outlook faces multiple structural pressures. The most closely watched is its excessive reliance on the AI capex cycle—related capex has grown nearly fivefold over the past three years, but the growth-boosting effect is expected to gradually fade after 2028. Volatility in tech stocks has yet to transmit to the dollar, but Deutsche Bank believes that a more pronounced downgrade in AI capex expectations would deliver a substantial shock to the dollar.
Meanwhile, the US fiscal deficit is stable at about 6% of GDP, and the current account deficit is widening again, approaching 4% of GDP—close to the worst in the G10. From a trade-weighted real exchange rate perspective, the underlying trade deficit has shown long-term structural deterioration, masked in headline data only by the US energy balance swinging from negative to positive. Tariff risk is another concern—historical experience in recent years shows that tariff threats tend to weigh on the dollar rather than lift it.
Asian Currencies: North Asian Capital Reallocation Sways the Dollar's Fate
North Asian currency moves are becoming an increasingly critical variable in the dollar outlook. The combined weight of the yen, won, and Taiwan dollar in the Fed's dollar index now exceeds that of the euro, and these economies are accumulating the world's largest trade surpluses. How these surpluses are deployed—recycled into the US, redirected elsewhere, or converted domestically—will have a decisive impact on the dollar.
Deutsche Bank defines this phenomenon as the "chip dollar" era: Chips account for roughly 50% of the value of every $1 of data center investment, chip manufacturing is concentrated in Asia, and the resulting trade surpluses are then recycled through investment in US capital markets—forming a self-reinforcing loop that also harbors systemic fragility that could unravel if AI valuations are repriced.
Specifically, Deutsche Bank expects USD/JPY to move toward the 140 range. BOJ rate hikes and government efforts to deploy savings domestically (including a deliberate push for GPIF to shift more assets into Japan) could trigger capital repatriation.
Euro: French Political Risk Weighs, But Improvement Is Possible
The euro will remain under pressure in the near term. The French presidential election (first round expected in April 2027) and the subsequent parliamentary elections constitute the primary source of uncertainty, likely keeping EUR/USD biased below 1.10 over the coming months. Market pricing currently implies more than 60 basis points of ECB hikes—far exceeding Deutsche Bank's forecast of 25 basis points—adding further drag on the euro.
However, Deutsche Bank believes the French election itself is more likely to be a market-clearing event than a risk amplifier. France's political risk premium is already fully reflected in the market, and French government bond spreads already carry a clear premium relative to fundamentals. Moreover, apart from the far left, all major French political forces have fiscal consolidation on their agendas, and fragmentation under a stable government scenario is unlikely to exceed current levels. Improving corporate profit trends and expanding both equity and bond inflows provide the basis for the euro's medium-term recovery. Deutsche Bank sees the full-year EUR/USD range at roughly 1.07 to 1.15.
Emerging Markets: Carry Room Narrows, Divergence Widens
After a strong year, the low-hanging fruit in EM FX is largely gone. Deutsche Bank has adopted a more cautious stance on CEEMEA and Latin American FX, mainly due to narrowing real rate differentials with the US, heavy positioning, and rising supply and fiscal risks.
Specifically, the Polish zloty, Czech koruna, and Israeli shekel face greater pressure from real rate differential compression; the Turkish lira, Egyptian pound, and South African rand are more sensitive to supply shocks. In Latin America, the Brazilian real remains supported by relatively high real rates and strong terms of trade, but fiscal risks have made the outlook more balanced; the Mexican peso continues to face pressure from weak economic growth and a dovish central bank stance; Andean currencies are relatively favored due to terms-of-trade tailwinds, cheap valuations, and potential reform dividends. Frontier markets remain a bright spot, but Deutsche Bank has tempered its bullish calls on the Kazakh tenge and Uzbek sum.
The AI boom is reshaping global capital flows. The dollar hovers at elevated levels, but its fragile support structure leaves the super-dollar outlook full of uncertainty.
According to Wind Trading Desk news, Deutsche Bank has sharply raised its 2027 dollar forecast in its latest FX outlook report, acknowledging that its previous call for a weaker dollar has fallen flat. The AI boom has pushed up US real rates, attracted massive equity inflows, rekindled inflation pressures, and prompted the Fed to turn hawkish—together forging the current "AI dollar" regime. The dollar is now more than 20% above its four-year average and ranks among the most expensive G10 currencies on all three fundamental valuation metrics.
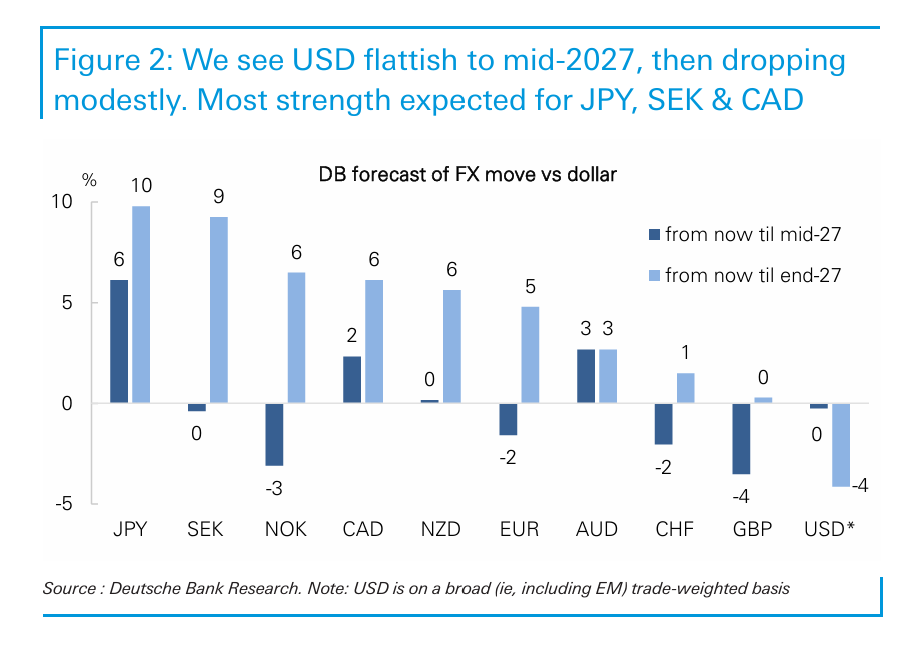
Deutsche Bank expects the dollar to extend its strength in the first half of 2027, post a modest pullback in the second half, but remain elevated overall. The report also warns that the dollar's dependence on the AI capex cycle is deepening. Should the market significantly cut its expectations for AI returns, the dollar's two supporting pillars—US real rates and equity inflows—would collapse in tandem, exposing the dollar to substantial downside risk.
AI Boom Underpins "Dollar Exceptionalism"
The core driver of dollar strength comes from within the US and could persist or even intensify in the near term. US inflation has re-accelerated over the past few months, with core PCE expected to breach 3%, driving a repricing in rates markets and pushing the dollar back into the top three highest-yielding G10 currencies—a status it had briefly ceded at the end of 2025. Deutsche Bank data shows that historically, the dollar has rarely entered a downcycle when offering high yields.
Rising real yields have simultaneously lifted US neutral rate expectations by about 50 basis points this year, while the euro area has remained virtually unchanged over the same period. Meanwhile, US GDP growth expectations have returned to the top of the G10, capex growth is roughly double that of other economies, and the AI-driven capacity expansion cycle lays the groundwork for productivity gains—all providing a positive incentive for the currency market.
Equity Inflows Dominate, Fixed-Income Flows Show Signs of Diversion
On the capital flow front, the US remains the core magnet for global equity investment. Foreign inflows into US equities have surpassed $1 trillion per year, becoming the primary source of financing for the US external deficit, and such flows typically carry low hedge ratios, providing a more direct boost to the dollar.
However, fixed-income flows are quietly shifting. Deutsche Bank data shows that US bond inflows have slowed, while bond inflows into other G10 markets such as Canada and Japan have rebounded significantly, shaking the "There Is No Alternative" (TINA) market narrative. FX reserve managers have also been steadily increasing allocations to other smaller currencies over the past year and a half. This trend warrants vigilance—if the diversification value of US dollar assets continues to decline, upward pressure on hedge ratios will increase accordingly.
High Valuations and Twin Deficits Pose Medium-Term Risks
The dollar's medium-term outlook faces multiple structural pressures. The most closely watched is its excessive reliance on the AI capex cycle—related capex has grown nearly fivefold over the past three years, but the growth-boosting effect is expected to gradually fade after 2028. Volatility in tech stocks has yet to transmit to the dollar, but Deutsche Bank believes that a more pronounced downgrade in AI capex expectations would deliver a substantial shock to the dollar.
Meanwhile, the US fiscal deficit is stable at about 6% of GDP, and the current account deficit is widening again, approaching 4% of GDP—close to the worst in the G10. From a trade-weighted real exchange rate perspective, the underlying trade deficit has shown long-term structural deterioration, masked in headline data only by the US energy balance swinging from negative to positive. Tariff risk is another concern—historical experience in recent years shows that tariff threats tend to weigh on the dollar rather than lift it.
Asian Currencies: North Asian Capital Reallocation Sways the Dollar's Fate
North Asian currency moves are becoming an increasingly critical variable in the dollar outlook. The combined weight of the yen, won, and Taiwan dollar in the Fed's dollar index now exceeds that of the euro, and these economies are accumulating the world's largest trade surpluses. How these surpluses are deployed—recycled into the US, redirected elsewhere, or converted domestically—will have a decisive impact on the dollar.
Deutsche Bank defines this phenomenon as the "chip dollar" era: Chips account for roughly 50% of the value of every $1 of data center investment, chip manufacturing is concentrated in Asia, and the resulting trade surpluses are then recycled through investment in US capital markets—forming a self-reinforcing loop that also harbors systemic fragility that could unravel if AI valuations are repriced.
Specifically, Deutsche Bank expects USD/JPY to move toward the 140 range. BOJ rate hikes and government efforts to deploy savings domestically (including a deliberate push for GPIF to shift more assets into Japan) could trigger capital repatriation.
Euro: French Political Risk Weighs, But Improvement Is Possible
The euro will remain under pressure in the near term. The French presidential election (first round expected in April 2027) and the subsequent parliamentary elections constitute the primary source of uncertainty, likely keeping EUR/USD biased below 1.10 over the coming months. Market pricing currently implies more than 60 basis points of ECB hikes—far exceeding Deutsche Bank's forecast of 25 basis points—adding further drag on the euro.
However, Deutsche Bank believes the French election itself is more likely to be a market-clearing event than a risk amplifier. France's political risk premium is already fully reflected in the market, and French government bond spreads already carry a clear premium relative to fundamentals. Moreover, apart from the far left, all major French political forces have fiscal consolidation on their agendas, and fragmentation under a stable government scenario is unlikely to exceed current levels. Improving corporate profit trends and expanding both equity and bond inflows provide the basis for the euro's medium-term recovery. Deutsche Bank sees the full-year EUR/USD range at roughly 1.07 to 1.15.
Emerging Markets: Carry Room Narrows, Divergence Widens
After a strong year, the low-hanging fruit in EM FX is largely gone. Deutsche Bank has adopted a more cautious stance on CEEMEA and Latin American FX, mainly due to narrowing real rate differentials with the US, heavy positioning, and rising supply and fiscal risks.
Specifically, the Polish zloty, Czech koruna, and Israeli shekel face greater pressure from real rate differential compression; the Turkish lira, Egyptian pound, and South African rand are more sensitive to supply shocks. In Latin America, the Brazilian real remains supported by relatively high real rates and strong terms of trade, but fiscal risks have made the outlook more balanced; the Mexican peso continues to face pressure from weak economic growth and a dovish central bank stance; Andean currencies are relatively favored due to terms-of-trade tailwinds, cheap valuations, and potential reform dividends. Frontier markets remain a bright spot, but Deutsche Bank has tempered its bullish calls on the Kazakh tenge and Uzbek sum.